APO RESEARCH · REPORT
High Molecular Weight Polyester Resin
High molecular weight polyester resins are linear or lightly branched condensation polymers formed through the polycondensation of diols and dicarboxylic acids or their functional derivatives.
Product & engineering
Understand the product.
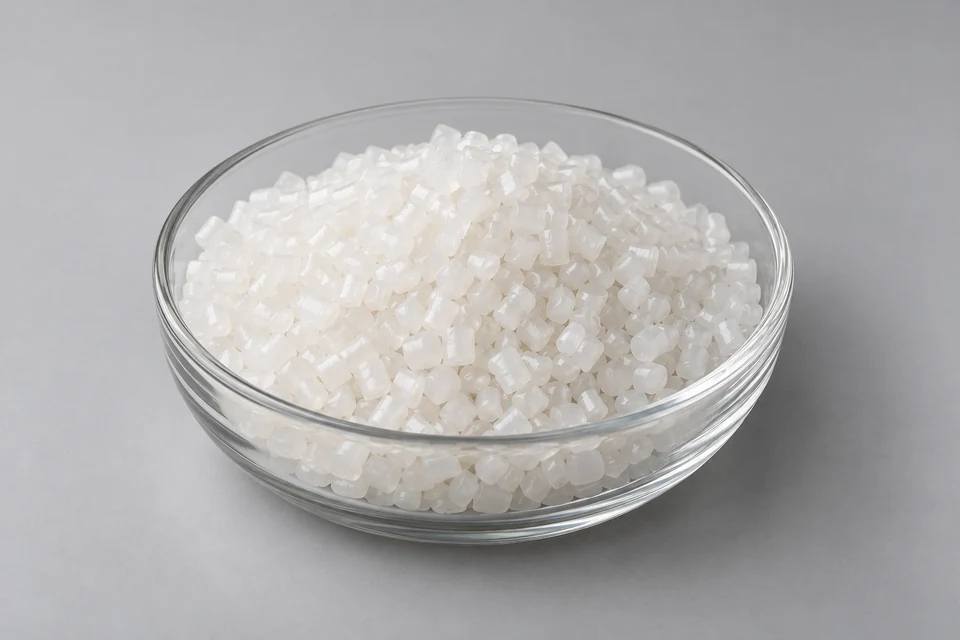
High molecular weight polyester resins are linear or lightly branched condensation polymers formed through the polycondensation of diols and dicarboxylic acids or their functional derivatives. These resins are defined by their relatively high molecular weight compared to application-specific norms, typically exhibiting number-average molecular weights (Mn) above 15,000 to 30,000 g/mol and weight-average molecular weights (Mw) that may range from 30,000 to over 100,000 g/mol. In industrial contexts, the designation “high molecular weight” does not imply a universal threshold, but rather describes polyester architectures with elevated melt viscosity, cohesive energy, and entanglement density. These molecular characteristics collectively enhance film formation, mechanical strength, chemical resistance, and dimensional stability across a wide array of end-use sectors. Depending on their macromolecular design and terminal group functionality, high molecular weight polyester resins are engineered either as thermoplastic engineering materials—such as polyethylene terephthalate (PET) and polybutylene terephthalate (PBT)—or as functionalized binders in coatings, adhesives, fibers, and composite systems.
The core monomer system for high molecular weight polyesters includes aromatic and aliphatic diacids such as purified terephthalic acid (PTA), isophthalic acid (IPA), phthalic anhydride (PA), adipic acid, and maleic anhydride, typically reacted with diols like ethylene glycol (EG), neopentyl glycol (NPG), 1,4-butanediol (BDO), and cyclohexanedimethanol (CHDM). In unsaturated systems, fumaric acid or maleic anhydride introduces reactive vinyl groups for free-radical crosslinking. Functional additives such as benzoic acid, trimellitic anhydride, or multifunctional polyols may be incorporated to adjust branching, reactivity, or flexibility. Catalyst selection—commonly involving antimony trioxide, titanium alkoxides, or organic tin compounds—directly influences polymer chain uniformity, discoloration, and target molecular weight.
Key physicochemical parameters govern the behavior and application windows of high molecular weight polyester resins. For coatings applications, carboxyl-terminated resins typically exhibit acid values (AV) between 0 and 15 mg KOH/g, while hydroxyl-terminated grades used in polyurethane or amino crosslinking systems show hydroxyl values (OHV) from 30 to 150 mg KOH/g. Melt viscosity varies by application and formulation, ranging from 1,000 to 10,000 mPa·s at 160–200°C for coatings, and from 100 to 300 Pa·s at 280°C for PET/PBT molding grades. Glass transition temperatures (Tg) typically range from 40°C to 80°C in amorphous resins for coatings, and from 70°C to 120°C in crystalline thermoplastics, depending on backbone rigidity and crystallinity. Intrinsic viscosity (IV), expressed in dL/g, is widely used as a proxy for molecular weight in PET systems, with high IV values between 0.4 and 0.8 dL/g indicating long-chain, process-stable polymers.
Commercially, high molecular weight polyester resins are manufactured through a two-stage melt polycondensation process. Initial esterification or transesterification occurs at 180–240°C, followed by high-temperature polycondensation at 250–280°C under vacuum (<5 mbar) to remove volatile condensates and promote molecular extension. For crystalline engineering polyesters such as PET and PBT, solid-state polymerization (SSP) is frequently applied post-melt to further increase molecular weight without inducing thermal degradation. In powder coatings, the resin is typically processed into flakes and micronized; in solventborne and high-solid systems, it is dissolved or dispersed into tailored carriers. Chain extenders and reactive diluents may be added to fine-tune final viscosity, reactivity, and film behavior.
High molecular weight polyesters are categorized according to their backbone saturation (saturated vs. unsaturated) and terminal functionality (e.g., hydroxyl-terminated, carboxyl-terminated, glycidyl-functionalized). Saturated thermoplastics such as PET and PBT are widely used in injection molding, extrusion, and fiber spinning, offering excellent strength-to-weight ratios, thermal performance, and dimensional stability. Unsaturated polyester resins (UPRs) of high molecular weight are used as matrix binders in fiber-reinforced thermoset systems for marine, construction, and automotive applications. Hydroxyl-terminated resins are widely employed in polyurethane or amino crosslinked coatings, offering high durability, chemical resistance, and UV performance. Carboxyl-terminated polyesters are used extensively in powder coatings, particularly in TGIC- or HAA-cured systems, valued for their low VOC content, gloss retention, and weatherability in architectural, appliance, and general industrial applications.
End-use applications are extensive and span across packaging, electronics, transportation, construction, printing, and healthcare. In the packaging sector, high IV PET resins are used for injection-stretch blow molded bottles and biaxially oriented films requiring clarity, impact resistance, and gas barrier properties. In flexible packaging and converting, high molecular weight polyesters are formulated into solventborne or waterborne adhesives and lamination binders for multilayer structures such as retort pouches, aluminum foil laminates, and heat-sealable films. In the coatings industry, they are widely used in coil coatings and can coatings, delivering corrosion resistance, chemical durability, and mechanical formability for pre-coated metals and food-contact surfaces. As ink binders, they enhance pigment dispersion, gloss, and adhesion in gravure and flexographic printing on plastic films, foils, and coated paper. In electronics and automotive interiors, amorphous and crystalline polyester resins are used in hot-melt adhesives, wire harness coatings, and flexible laminates where thermal stability and dimensional accuracy are critical. They are also employed in magnetic coatings, thermal transfer layers, and optical films requiring high transparency and anti-curling properties. In textiles and fibers, water-dispersible polyester resins are used for fiber sizing, fabric backings, and anti-static finishing. Additionally, medical-grade resins are used in hygienic films, breathable membranes, and skin-contact adhesives due to their high purity, molecular integrity, and film flexibility.
The global supply chain for high molecular weight polyester resins is anchored by upstream production of PTA, IPA, EG, and specialty diols, with polymerization operations concentrated among major resin manufacturers in East Asia, Western Europe, and North America. Key producers include Mitsubishi Chemical, Eastman Chemical, Arkema, Macroocean, Covestro, SKC, and Toyobo. Collectively, these companies supply tens of millions of tons annually, with high molecular weight grades commanding strategic positions in functional coatings, engineered plastics, and high-barrier packaging. As the industry moves toward circularity and performance differentiation, sustainable innovations such as bio-based PEF, chemical recycling of PET oligomers, and hybrid copolymer systems are gaining commercial momentum. These developments underscore the critical role of high molecular weight polyester resins not only as structural materials, but as customizable functional platforms adaptable to the increasingly complex requirements of modern industrial applications.
High Molecular Weight Polyester Resin has become a key film-forming material in high-end formulations for coatings, adhesives, inks, and functional films. Between 2020 and 2025, the global market underwent structural evolution shaped by raw material price volatility, tightening environmental regulations, and shifting application demand. According to APO Research, global consumption is projected to reach 163,357 tons in 2025, with a total market value of USD 472 million, reflecting an average price of USD 2,886 per ton—a 16.1% increase over 2020 levels. From 2020 to 2024, the market grew at a compound annual growth rate (CAGR) of 6.28% in value and 2.40% in volume. Looking ahead to 2025–2031, these rates are expected to rise to 7.34% and 3.63%, respectively, indicating a shift toward quality-driven structural growth.
From a technical segmentation perspective, the market is primarily composed of three categories: solvent-based, hot-melt crystallizable, and water-soluble/water-dispersible systems. Solvent-based resins currently retain a dominant share, with 2025 volume reaching 83,463 tons, though their share is being rapidly eroded by hot-melt crystallizable (53,142 tons) and water-dispersible (26,752 tons) alternatives. Particularly, water-dispersible systems are experiencing accelerated adoption due to regulatory pressures and the green transformation of end-use industries. This segment is forecast to grow at a CAGR of 7.57% in value from 2025 to 2031, positioning it as a key driver of structural growth. The average prices also vary significantly across technologies—USD 3,583/ton for water-dispersible, USD 3,090/ton for hot-melt crystallizable, and USD 2,533/ton for solvent-based—reflecting differences in technological complexity, environmental value, and downstream purchasing willingness.
In terms of end-use applications, demand is concentrated in eight primary sectors, led by coil and can coatings, which are expected to reach 42,800 tons in 2025 with a market value of USD 102.3 million, rising to USD 159 million by 2031. These coatings serve downstream markets such as building-grade color steel panels and tinplate packaging, requiring high mechanical properties, weather resistance, and processing stability. Following closely are adhesives for flexible packaging (31,038 tons) and ink binders (26,153 tons), widely used in food-grade laminates and industrial labeling. Their formulations demand low VOC, water dispersibility, and gloss stability, which are accelerating the adoption of water-based systems. Other functional segments—such as dry lamination adhesives, hot-melt adhesives, optical films, and medical & hygiene adhesives—are gaining share at moderate to high growth rates, contributing to the market's structural upgrade.
Regionally, mainland China stands as the largest global production and consumption hub, with demand reaching 53,752 tons in 2025, accounting for 32.9% of global volume, and is the only major market with above-average growth (2025–2031 CAGR: 4.42%). Other Asian economies, including Japan, Southeast Asia, and India, are building integrated supply chains, gradually reducing reliance on exports from North America and Europe. Western markets, on the other hand, are characterized by price premiums and a higher share of high-end applications, with above-average unit prices and a focus on specialty coatings, electronics, and premium packaging.
In terms of market structure, the global High Molecular Weight Polyester Resin industry shows moderate concentration, with the top five players—Evonik, Eternal Materials, Toyobo, Covestro, and Arkema—collectively holding approximately 50% market share. Evonik and Eternal Materials maintain leading positions with annual sales exceeding 20,000 tons, while Toyobo has demonstrated rapid penetration in the water-dispersible segment. Asian-based suppliers, such as Macroocean, SK Chemicals, Mitsubishi Chemical, Chansieh Enterprises, and Daily Polymer, are increasingly overcoming product limitations, showing strong capacity for both import substitution and export expansion. Although most production capacity is concentrated in technologically advanced regions such as China, Japan, Germany, South Korea, and Taiwan, export dependency is gradually declining as regional supply chains gain independence.
In terms of pricing trends, the market experienced a significant surge between 2020 and 2022 (peaking at USD 3,111/ton in 2022), followed by a slight correction in 2023–2024. However, overall price levels have risen well above pre-2019 benchmarks. Looking forward, average prices are expected to increase steadily, driven by the rising share of high-value-added products and changes in feedstock structure. By 2031, the weighted average price is projected to reach USD 3,564/ton. As solvent-based resins face growing environmental burdens and the technical thresholds of water-dispersible and hot-melt resins continue to climb, price stratification will intensify, leading to a redistribution of profit margins.
The year 2025 will mark a turning point for the global High Molecular Weight Polyester Resin industry, as the market transitions from volume-driven growth to a phase characterized by structural and performance-driven upgrades. By 2031, the global market is projected to reach USD 721 million, with structural growth primarily driven by emerging high-end applications such as green coatings, low-migration adhesive systems, biodegradable functional films, and electronic/optical substrates. Going forward, the key to technological competitiveness will not lie in capacity expansion alone but in differentiated product portfolios, regulatory compliance, and cross-disciplinary formulation synergy across coating, adhesive, and film systems.
Composition, supplied form and processing history determine the usable material. Evaluate the property required by the actual application with the specified test method; a chemistry name alone does not define a finished grade.
What turns activity into demand
Qualified formulation or component output creates material purchases through loading, process yield and the supplied mass basis. Raw material, formulated blend and finished-part revenues describe separate transaction stages.
The commercial boundary
For High Molecular Weight Polyester Resin, distinguish the supplied product from its inputs and the complete application. Report types and applications may overlap; retain the selected edition's product definition, geography, period, unit and transaction basis when comparing estimates.
Which conditions determine usable high molecular weight polyester resin performance?
High molecular weight polyester resins are linear or lightly branched condensation polymers formed through the polycondensation of diols and dicarboxylic acids or their functional derivatives. Match formulation and impurity limits to the converting process, then verify the property after processing or curing. Compare like-for-like dry or as-supplied quantities; a finished component and its raw material represent different transaction stages.
Selected research
Industry Research
High Molecular Weight Polyester Resin Industry Research Report 2026
Market perspective
High molecular weight polyester resins are linear or lightly branched condensation polymers formed through the polycondensation of diols and dicarboxylic acids or their functional derivatives. These resins are defined by their relatively high molecular weight compared to application-specific norms, typically exhibiting number-average molecular weights (Mn) above 15,000 to 30,000 g/mol and weight-average molecular weights (Mw) that may range from 30,000 to over 100,000 g/mol. In industrial contexts, the designation “high molecular weight” does not imply a universal threshold, but rather describes polyester architectures with elevated melt viscosity, cohesive energy, and entanglement density. These molecular characteristics collectively enhance film formation, mechanical strength, chemical resistance, and dimensional stability across a wide array of end-use sectors. Depending on their macromolecular design and terminal group functionality, high molecular weight polyester resins are engineered either as thermoplastic engineering materials—such as polyethylene terephthalate (PET) and polybutylene terephthalate (PBT)—or as functionalized binders in coatings, adhesives, fibers, and composite systems.
The core monomer system for high molecular weight polyesters includes aromatic and aliphatic diacids such as purified terephthalic acid (PTA), isophthalic acid (IPA), phthalic anhydride (PA), adipic acid, and maleic anhydride, typically reacted with diols like ethylene glycol (EG), neopentyl glycol (NPG), 1,4-butanediol (BDO), and cyclohexanedimethanol (CHDM). In unsaturated systems, fumaric acid or maleic anhydride introduces reactive vinyl groups for free-radical crosslinking. Functional additives such as benzoic acid, trimellitic anhydride, or multifunctional polyols may be incorporated to adjust branching, reactivity, or flexibility. Catalyst selection—commonly involving antimony trioxide, titanium alkoxides, or organic tin compounds—directly influences polymer chain uniformity, discoloration, and target molecular weight.
Key physicochemical parameters govern the behavior and application windows of high molecular weight polyester resins. For coatings applications, carboxyl-terminated resins typically exhibit acid values (AV) between 0 and 15 mg KOH/g, while hydroxyl-terminated grades used in polyurethane or amino crosslinking systems show hydroxyl values (OHV) from 30 to 150 mg KOH/g. Melt viscosity varies by application and formulation, ranging from 1,000 to 10,000 mPa·s at 160–200°C for coatings, and from 100 to 300 Pa·s at 280°C for PET/PBT molding grades. Glass transition temperatures (Tg) typically range from 40°C to 80°C in amorphous resins for coatings, and from 70°C to 120°C in crystalline thermoplastics, depending on backbone rigidity and crystallinity. Intrinsic viscosity (IV), expressed in dL/g, is widely used as a proxy for molecular weight in PET systems, with high IV values between 0.4 and 0.8 dL/g indicating long-chain, process-stable polymers.
Read the full market overview
Commercially, high molecular weight polyester resins are manufactured through a two-stage melt polycondensation process. Initial esterification or transesterification occurs at 180–240°C, followed by high-temperature polycondensation at 250–280°C under vacuum (<5 mbar) to remove volatile condensates and promote molecular extension. For crystalline engineering polyesters such as PET and PBT, solid-state polymerization (SSP) is frequently applied post-melt to further increase molecular weight without inducing thermal degradation. In powder coatings, the resin is typically processed into flakes and micronized; in solventborne and high-solid systems, it is dissolved or dispersed into tailored carriers. Chain extenders and reactive diluents may be added to fine-tune final viscosity, reactivity, and film behavior.
High molecular weight polyesters are categorized according to their backbone saturation (saturated vs. unsaturated) and terminal functionality (e.g., hydroxyl-terminated, carboxyl-terminated, glycidyl-functionalized). Saturated thermoplastics such as PET and PBT are widely used in injection molding, extrusion, and fiber spinning, offering excellent strength-to-weight ratios, thermal performance, and dimensional stability. Unsaturated polyester resins (UPRs) of high molecular weight are used as matrix binders in fiber-reinforced thermoset systems for marine, construction, and automotive applications. Hydroxyl-terminated resins are widely employed in polyurethane or amino crosslinked coatings, offering high durability, chemical resistance, and UV performance. Carboxyl-terminated polyesters are used extensively in powder coatings, particularly in TGIC- or HAA-cured systems, valued for their low VOC content, gloss retention, and weatherability in architectural, appliance, and general industrial applications.
End-use applications are extensive and span across packaging, electronics, transportation, construction, printing, and healthcare. In the packaging sector, high IV PET resins are used for injection-stretch blow molded bottles and biaxially oriented films requiring clarity, impact resistance, and gas barrier properties. In flexible packaging and converting, high molecular weight polyesters are formulated into solventborne or waterborne adhesives and lamination binders for multilayer structures such as retort pouches, aluminum foil laminates, and heat-sealable films. In the coatings industry, they are widely used in coil coatings and can coatings, delivering corrosion resistance, chemical durability, and mechanical formability for pre-coated metals and food-contact surfaces. As ink binders, they enhance pigment dispersion, gloss, and adhesion in gravure and flexographic printing on plastic films, foils, and coated paper. In electronics and automotive interiors, amorphous and crystalline polyester resins are used in hot-melt adhesives, wire harness coatings, and flexible laminates where thermal stability and dimensional accuracy are critical. They are also employed in magnetic coatings, thermal transfer layers, and optical films requiring high transparency and anti-curling properties. In textiles and fibers, water-dispersible polyester resins are used for fiber sizing, fabric backings, and anti-static finishing. Additionally, medical-grade resins are used in hygienic films, breathable membranes, and skin-contact adhesives due to their high purity, molecular integrity, and film flexibility.
The global supply chain for high molecular weight polyester resins is anchored by upstream production of PTA, IPA, EG, and specialty diols, with polymerization operations concentrated among major resin manufacturers in East Asia, Western Europe, and North America. Key producers include Mitsubishi Chemical, Eastman Chemical, Arkema, Macroocean, Covestro, SKC, and Toyobo. Collectively, these companies supply tens of millions of tons annually, with high molecular weight grades commanding strategic positions in functional coatings, engineered plastics, and high-barrier packaging. As the industry moves toward circularity and performance differentiation, sustainable innovations such as bio-based PEF, chemical recycling of PET oligomers, and hybrid copolymer systems are gaining commercial momentum. These developments underscore the critical role of high molecular weight polyester resins not only as structural materials, but as customizable functional platforms adaptable to the increasingly complex requirements of modern industrial applications.
High Molecular Weight Polyester Resin has become a key film-forming material in high-end formulations for coatings, adhesives, inks, and functional films. Between 2020 and 2025, the global market underwent structural evolution shaped by raw material price volatility, tightening environmental regulations, and shifting application demand. According to APO Research, global consumption is projected to reach 163,357 tons in 2025, with a total market value of USD 472 million, reflecting an average price of USD 2,886 per ton—a 16.1% increase over 2020 levels. From 2020 to 2024, the market grew at a compound annual growth rate (CAGR) of 6.28% in value and 2.40% in volume. Looking ahead to 2025–2031, these rates are expected to rise to 7.34% and 3.63%, respectively, indicating a shift toward quality-driven structural growth.
From a technical segmentation perspective, the market is primarily composed of three categories: solvent-based, hot-melt crystallizable, and water-soluble/water-dispersible systems. Solvent-based resins currently retain a dominant share, with 2025 volume reaching 83,463 tons, though their share is being rapidly eroded by hot-melt crystallizable (53,142 tons) and water-dispersible (26,752 tons) alternatives. Particularly, water-dispersible systems are experiencing accelerated adoption due to regulatory pressures and the green transformation of end-use industries. This segment is forecast to grow at a CAGR of 7.57% in value from 2025 to 2031, positioning it as a key driver of structural growth. The average prices also vary significantly across technologies—USD 3,583/ton for water-dispersible, USD 3,090/ton for hot-melt crystallizable, and USD 2,533/ton for solvent-based—reflecting differences in technological complexity, environmental value, and downstream purchasing willingness.
In terms of end-use applications, demand is concentrated in eight primary sectors, led by coil and can coatings, which are expected to reach 42,800 tons in 2025 with a market value of USD 102.3 million, rising to USD 159 million by 2031. These coatings serve downstream markets such as building-grade color steel panels and tinplate packaging, requiring high mechanical properties, weather resistance, and processing stability. Following closely are adhesives for flexible packaging (31,038 tons) and ink binders (26,153 tons), widely used in food-grade laminates and industrial labeling. Their formulations demand low VOC, water dispersibility, and gloss stability, which are accelerating the adoption of water-based systems. Other functional segments—such as dry lamination adhesives, hot-melt adhesives, optical films, and medical & hygiene adhesives—are gaining share at moderate to high growth rates, contributing to the market's structural upgrade.
Regionally, mainland China stands as the largest global production and consumption hub, with demand reaching 53,752 tons in 2025, accounting for 32.9% of global volume, and is the only major market with above-average growth (2025–2031 CAGR: 4.42%). Other Asian economies, including Japan, Southeast Asia, and India, are building integrated supply chains, gradually reducing reliance on exports from North America and Europe. Western markets, on the other hand, are characterized by price premiums and a higher share of high-end applications, with above-average unit prices and a focus on specialty coatings, electronics, and premium packaging.
In terms of market structure, the global High Molecular Weight Polyester Resin industry shows moderate concentration, with the top five players—Evonik, Eternal Materials, Toyobo, Covestro, and Arkema—collectively holding approximately 50% market share. Evonik and Eternal Materials maintain leading positions with annual sales exceeding 20,000 tons, while Toyobo has demonstrated rapid penetration in the water-dispersible segment. Asian-based suppliers, such as Macroocean, SK Chemicals, Mitsubishi Chemical, Chansieh Enterprises, and Daily Polymer, are increasingly overcoming product limitations, showing strong capacity for both import substitution and export expansion. Although most production capacity is concentrated in technologically advanced regions such as China, Japan, Germany, South Korea, and Taiwan, export dependency is gradually declining as regional supply chains gain independence.
In terms of pricing trends, the market experienced a significant surge between 2020 and 2022 (peaking at USD 3,111/ton in 2022), followed by a slight correction in 2023–2024. However, overall price levels have risen well above pre-2019 benchmarks. Looking forward, average prices are expected to increase steadily, driven by the rising share of high-value-added products and changes in feedstock structure. By 2031, the weighted average price is projected to reach USD 3,564/ton. As solvent-based resins face growing environmental burdens and the technical thresholds of water-dispersible and hot-melt resins continue to climb, price stratification will intensify, leading to a redistribution of profit margins.
The year 2025 will mark a turning point for the global High Molecular Weight Polyester Resin industry, as the market transitions from volume-driven growth to a phase characterized by structural and performance-driven upgrades. By 2031, the global market is projected to reach USD 721 million, with structural growth primarily driven by emerging high-end applications such as green coatings, low-migration adhesive systems, biodegradable functional films, and electronic/optical substrates. Going forward, the key to technological competitiveness will not lie in capacity expansion alone but in differentiated product portfolios, regulatory compliance, and cross-disciplinary formulation synergy across coating, adhesive, and film systems.
The global High Molecular Weight Polyester Resin market was valued at US$ million in 2025 and is projected to reach US$ million by 2032, implying a CAGR of % over 2026–2032.
The North America market for High Molecular Weight Polyester Resin is forecast to increase from US$ million in 2026 to US$ million by 2032, corresponding to a CAGR of % over 2026–2032.
The Europe market for High Molecular Weight Polyester Resin is projected to rise from US$ million in 2026 to US$ million by 2032, registering a CAGR of % over 2026–2032.
The Asia Pacific market for High Molecular Weight Polyester Resin is expected to grow from US$ million in 2026 to US$ million by 2032, at a CAGR of % over 2026–2032.
Leading global manufacturers of High Molecular Weight Polyester Resin include , among others. In 2025, the top three vendors together accounted for approximately % of global revenue.
Report Scope
This report quantifies the global High Molecular Weight Polyester Resin market in revenue (US$ million) and, where applicable, sales volume (tons), using 2025 as the base year and providing annual historical and forecast data for 2021–2032.
It standardizes definitions of types and applications, harmonizes vendor attribution, and presents comparable time series by company, type, application, and region/country, including indicative price bands (US$/tons) and concentration ratios (CR5/CR10).
The outputs are intended to support strategy development, budgeting, and performance benchmarking for manufacturers, new entrants, channel partners, and investors; the report also reviews technology shifts and notable product introductions relevant to High Molecular Weight Polyester Resin.
Key Companies & Market Share Insights
This section profiles leading manufacturers, combining 2021–2025 results with a 2026–2032 outlook. It reports revenue, market share, price bands, product and application mix, regional and channel mix, and key developments (M&A, capacity additions, certifications). It also provides global revenue, average price, and—where applicable—sales volume by manufacturer, and calculates CR5/CR10 and rank changes to support comparative benchmarking.
High Molecular Weight Polyester Resin Market by Company
Evonik
Eternal Materials
Toyobo
Covestro
Arkema
SK Chemicals
Mitsubishi Chemical
Allnex
Macroocean
Eastman
Chansieh Enterprises
Goo Chemical
Daily Polymer
High Molecular Weight Polyester Resin Segment by Type
Solvent-soluble Type
Crystalline Hot-Melt Type
Water-soluble Type
High Molecular Weight Polyester Resin Segment by Application
Coil & Can Coatings
Flexible Packaging Adhesives
Printing Ink Binders
Dry Lamination Adhesives
Hot-Melt Adhesives for Cables, Paper, Textiles
Fiber & Film Surface Treatment
Magnetic Coatings / Optical Films
Medical Films / Hygiene Adhesives
High Molecular Weight Polyester Resin Segment by Region
North America
United States
Canada
Mexico
Europe
Germany
France
U.K.
Italy
Russia
Spain
Netherlands
Switzerland
Sweden
Poland
Asia-Pacific
China
Japan
South Korea
India
Australia
Taiwan
Southeast Asia
South America
Brazil
Argentina
Chile
Middle East & Africa
Egypt
South Africa
Israel
Türkiye
GCC Countries
Key Drivers & Barriers
High-impact rendering factors and drivers have been studied in this report to aid the readers to understand the general development. Moreover, the report includes restraints and challenges that may act as stumbling blocks on the way of the players. This will assist the users to be attentive and make informed decisions related to business. Specialists have also laid their focus on the upcoming business prospects.
Reasons to Buy This Report
1. This report will help the readers to understand the competition within the industries and strategies for the competitive environment to enhance the potential profit. The report also focuses on the competitive landscape of the global High Molecular Weight Polyester Resin market, and introduces in detail the market share, industry ranking, competitor ecosystem, market performance, new product development, operation situation, expansion, and acquisition. etc. of the main players, which helps the readers to identify the main competitors and deeply understand the competition pattern of the market.
2. This report will help stakeholders to understand the global industry status and trends of High Molecular Weight Polyester Resin and provides them with information on key market drivers, restraints, challenges, and opportunities.
3. This report will help stakeholders to understand competitors better and gain more insights to strengthen their position in their businesses. The competitive landscape section includes the market share and rank (in volume and value), competitor ecosystem, new product development, expansion, and acquisition.
4. This report stays updated with novel technology integration, features, and the latest developments in the market
5. This report helps stakeholders to gain insights into which regions to target globally
6. This report helps stakeholders to gain insights into the end-user perception concerning the adoption of High Molecular Weight Polyester Resin.
7. This report helps stakeholders to identify some of the key players in the market and understand their valuable contribution.
Chapter Outline
Chapter 1: Research objectives, research methods, data sources, data cross-validation;
Chapter 2: Introduces the report scope of the report, executive summary of different market segments (by region, product type, application, etc), including the market size of each market segment, future development potential, and so on. It offers a high-level view of the current state of the market and its likely evolution in the short to mid-term, and long term.
Chapter 3: Detailed analysis of High Molecular Weight Polyester Resin manufacturers competitive landscape, price, production and value market share, latest development plan, merger, and acquisition information, etc.
Chapter 4: Provides profiles of key players, introducing the basic situation of the main companies in the market in detail, including product production/output, value, price, gross margin, product introduction, recent development, etc.
Chapter 5: Production/output, value of High Molecular Weight Polyester Resin by region/country. It provides a quantitative analysis of the market size and development potential of each region in the next six years.
Chapter 6: Consumption of High Molecular Weight Polyester Resin in regional level and country level. It provides a quantitative analysis of the market size and development potential of each region and its main countries and introduces the market development, future development prospects, market space, and production of each country in the world.
Chapter 7: Provides the analysis of various market segments by type, covering the market size and development potential of each market segment, to help readers find the blue ocean market in different market segments.
Chapter 8: Provides the analysis of various market segments by application, covering the market size and development potential of each market segment, to help readers find the blue ocean market in different downstream markets.
Chapter 9: Analysis of industrial chain, including the upstream and downstream of the industry.
Chapter 10: Introduces the market dynamics, latest developments of the market, the driving factors and restrictive factors of the market, the challenges and risks faced by manufacturers in the industry, and the analysis of relevant policies in the industry.
Chapter 11: The main points and conclusions of the report.
More report detail
Tables and figures
Scope & coverage.
Types
- Solvent-soluble Type
- Crystalline Hot-Melt Type
- Water-soluble Type
Applications
- Coil & Can Coatings
- Flexible Packaging Adhesives
- Printing Ink Binders
- Dry Lamination Adhesives
- Hot-Melt Adhesives for Cables, Paper, Textiles
- Fiber & Film Surface Treatment
- Magnetic Coatings / Optical Films
- Medical Films / Hygiene Adhesives
Companies covered
- Evonik
- Eternal Materials
- Toyobo
- Covestro
- Arkema
- SK Chemicals
- Mitsubishi Chemical
- Allnex
- Macroocean
- Eastman
- Chansieh Enterprises
- Goo Chemical
- Daily Polymer
Inside the report.
1 Preface
- 1.1 Scope of Report
- 1.2 Reasons for Doing This Study
- 1.3 Research Methodology
- 1.4 Research Process
- 1.5 Data Source
- 1.5.1 Secondary Sources
- 1.5.2 Primary Sources
2 Market Overview
- 2.1 Product Definition
- 2.2 High Molecular Weight Polyester Resin by Type
- 2.2.1 Market Value Comparison by Type (2021 VS 2025 VS 2032) & (US$ Million)
- 2.2.2 Solvent-soluble Type
- 2.2.3 Crystalline Hot-Melt Type
- 2.2.4 Water-soluble Type
- 2.3 High Molecular Weight Polyester Resin by Application
- 2.3.1 Market Value Comparison by Application (2021 VS 2025 VS 2032) & (US$ Million)
- 2.3.2 Coil & Can Coatings
- 2.3.3 Flexible Packaging Adhesives
- 2.3.4 Printing Ink Binders
- 2.3.5 Dry Lamination Adhesives
- 2.3.6 Hot-Melt Adhesives for Cables, Paper, Textiles
- 2.3.7 Fiber & Film Surface Treatment
- 2.3.8 Magnetic Coatings / Optical Films
- 2.3.9 Medical Films / Hygiene Adhesives
- 2.4 Global Market Growth Prospects
- 2.4.1 Global High Molecular Weight Polyester Resin Production Value Estimates and Forecasts (2021-2032)
- 2.4.2 Global High Molecular Weight Polyester Resin Production Capacity Estimates and Forecasts (2021-2032)
- 2.4.3 Global High Molecular Weight Polyester Resin Production Estimates and Forecasts (2021-2032)
- 2.4.4 Global High Molecular Weight Polyester Resin Market Average Price (2021-2032)
3 Market Competitive Landscape by Manufacturers
- 3.1 Global High Molecular Weight Polyester Resin Production by Manufacturers (2021-2026)
- 3.2 Global High Molecular Weight Polyester Resin Production Value by Manufacturers (2021-2026)
- 3.3 Global High Molecular Weight Polyester Resin Average Price by Manufacturers (2021-2026)
- 3.4 Global High Molecular Weight Polyester Resin Industry Manufacturers Ranking, 2024 VS 2025 VS 2026
- 3.5 Global High Molecular Weight Polyester Resin Key Manufacturers, Manufacturing Sites & Headquarters
- 3.6 Global High Molecular Weight Polyester Resin Manufacturers, Product Type & Application
- 3.7 Global High Molecular Weight Polyester Resin Manufacturers Established Date
- 3.8 Global High Molecular Weight Polyester Resin Market CR5 and HHI
- 3.9 Global Manufacturers Mergers & Acquisition
4 Manufacturers Profiled
- 4.1 Evonik
- 4.1.1 Evonik High Molecular Weight Polyester Resin Company Information
- 4.1.2 Evonik High Molecular Weight Polyester Resin Business Overview
- 4.1.3 Evonik High Molecular Weight Polyester Resin Production Capacity, Value and Gross Margin (2021-2026)
- 4.1.4 Evonik Product Portfolio
- 4.1.5 Evonik Recent Developments
- 4.2 Eternal Materials
- 4.2.1 Eternal Materials High Molecular Weight Polyester Resin Company Information
- 4.2.2 Eternal Materials High Molecular Weight Polyester Resin Business Overview
- 4.2.3 Eternal Materials High Molecular Weight Polyester Resin Production Capacity, Value and Gross Margin (2021-2026)
- 4.2.4 Eternal Materials Product Portfolio
- 4.2.5 Eternal Materials Recent Developments
- 4.3 Toyobo
- 4.3.1 Toyobo High Molecular Weight Polyester Resin Company Information
- 4.3.2 Toyobo High Molecular Weight Polyester Resin Business Overview
- 4.3.3 Toyobo High Molecular Weight Polyester Resin Production Capacity, Value and Gross Margin (2021-2026)
- 4.3.4 Toyobo Product Portfolio
- 4.3.5 Toyobo Recent Developments
- 4.4 Covestro
- 4.4.1 Covestro High Molecular Weight Polyester Resin Company Information
- 4.4.2 Covestro High Molecular Weight Polyester Resin Business Overview
- 4.4.3 Covestro High Molecular Weight Polyester Resin Production Capacity, Value and Gross Margin (2021-2026)
- 4.4.4 Covestro Product Portfolio
- 4.4.5 Covestro Recent Developments
- 4.5 Arkema
- 4.5.1 Arkema High Molecular Weight Polyester Resin Company Information
- 4.5.2 Arkema High Molecular Weight Polyester Resin Business Overview
- 4.5.3 Arkema High Molecular Weight Polyester Resin Production Capacity, Value and Gross Margin (2021-2026)
- 4.5.4 Arkema Product Portfolio
- 4.5.5 Arkema Recent Developments
- 4.6 SK Chemicals
- 4.6.1 SK Chemicals High Molecular Weight Polyester Resin Company Information
- 4.6.2 SK Chemicals High Molecular Weight Polyester Resin Business Overview
- 4.6.3 SK Chemicals High Molecular Weight Polyester Resin Production Capacity, Value and Gross Margin (2021-2026)
- 4.6.4 SK Chemicals Product Portfolio
- 4.6.5 SK Chemicals Recent Developments
- 4.7 Mitsubishi Chemical
- 4.7.1 Mitsubishi Chemical High Molecular Weight Polyester Resin Company Information
- 4.7.2 Mitsubishi Chemical High Molecular Weight Polyester Resin Business Overview
- 4.7.3 Mitsubishi Chemical High Molecular Weight Polyester Resin Production Capacity, Value and Gross Margin (2021-2026)
- 4.7.4 Mitsubishi Chemical Product Portfolio
- 4.7.5 Mitsubishi Chemical Recent Developments
- 4.8 Allnex
- 4.8.1 Allnex High Molecular Weight Polyester Resin Company Information
- 4.8.2 Allnex High Molecular Weight Polyester Resin Business Overview
- 4.8.3 Allnex High Molecular Weight Polyester Resin Production Capacity, Value and Gross Margin (2021-2026)
- 4.8.4 Allnex Product Portfolio
- 4.8.5 Allnex Recent Developments
- 4.9 Macroocean
- 4.9.1 Macroocean High Molecular Weight Polyester Resin Company Information
- 4.9.2 Macroocean High Molecular Weight Polyester Resin Business Overview
- 4.9.3 Macroocean High Molecular Weight Polyester Resin Production Capacity, Value and Gross Margin (2021-2026)
- 4.9.4 Macroocean Product Portfolio
- 4.9.5 Macroocean Recent Developments
- 4.10 Eastman
- 4.10.1 Eastman High Molecular Weight Polyester Resin Company Information
- 4.10.2 Eastman High Molecular Weight Polyester Resin Business Overview
- 4.10.3 Eastman High Molecular Weight Polyester Resin Production Capacity, Value and Gross Margin (2021-2026)
- 4.10.4 Eastman Product Portfolio
- 4.10.5 Eastman Recent Developments
- 4.11 Chansieh Enterprises
- 4.11.1 Chansieh Enterprises High Molecular Weight Polyester Resin Company Information
- 4.11.2 Chansieh Enterprises High Molecular Weight Polyester Resin Business Overview
- 4.11.3 Chansieh Enterprises High Molecular Weight Polyester Resin Production Capacity, Value and Gross Margin (2021-2026)
- 4.11.4 Chansieh Enterprises Product Portfolio
- 4.11.5 Chansieh Enterprises Recent Developments
- 4.12 Goo Chemical
- 4.12.1 Goo Chemical High Molecular Weight Polyester Resin Company Information
- 4.12.2 Goo Chemical High Molecular Weight Polyester Resin Business Overview
- 4.12.3 Goo Chemical High Molecular Weight Polyester Resin Production Capacity, Value and Gross Margin (2021-2026)
- 4.12.4 Goo Chemical Product Portfolio
- 4.12.5 Goo Chemical Recent Developments
- 4.13 Daily Polymer
- 4.13.1 Daily Polymer High Molecular Weight Polyester Resin Company Information
- 4.13.2 Daily Polymer High Molecular Weight Polyester Resin Business Overview
- 4.13.3 Daily Polymer High Molecular Weight Polyester Resin Production Capacity, Value and Gross Margin (2021-2026)
- 4.13.4 Daily Polymer Product Portfolio
- 4.13.5 Daily Polymer Recent Developments
5 Global High Molecular Weight Polyester Resin Production by Region
- 5.1 Global High Molecular Weight Polyester Resin Production Estimates and Forecasts by Region: 2021 VS 2025 VS 2032
- 5.2 Global High Molecular Weight Polyester Resin Production by Region: 2021-2032
- 5.2.1 Global High Molecular Weight Polyester Resin Production by Region: 2021-2026
- 5.2.2 Global High Molecular Weight Polyester Resin Production Forecast by Region (2027-2032)
- 5.3 Global High Molecular Weight Polyester Resin Production Value Estimates and Forecasts by Region: 2021 VS 2025 VS 2032
- 5.4 Global High Molecular Weight Polyester Resin Production Value by Region: 2021-2032
- 5.4.1 Global High Molecular Weight Polyester Resin Production Value by Region: 2021-2026
- 5.4.2 Global High Molecular Weight Polyester Resin Production Value Forecast by Region (2027-2032)
- 5.5 Global High Molecular Weight Polyester Resin Market Price Analysis by Region (2021-2026)
- 5.6 Global High Molecular Weight Polyester Resin Production and Value, YOY Growth
- 5.6.1 North America High Molecular Weight Polyester Resin Production Value Estimates and Forecasts (2021-2032)
- 5.6.2 Europe High Molecular Weight Polyester Resin Production Value Estimates and Forecasts (2021-2032)
- 5.6.3 China High Molecular Weight Polyester Resin Production Value Estimates and Forecasts (2021-2032)
- 5.6.4 Japan High Molecular Weight Polyester Resin Production Value Estimates and Forecasts (2021-2032)
6 Global High Molecular Weight Polyester Resin Consumption by Region
- 6.1 Global High Molecular Weight Polyester Resin Consumption Estimates and Forecasts by Region: 2021 VS 2025 VS 2032
- 6.2 Global High Molecular Weight Polyester Resin Consumption by Region (2021-2032)
- 6.2.1 Global High Molecular Weight Polyester Resin Consumption by Region: 2021-2026
- 6.2.2 Global High Molecular Weight Polyester Resin Forecasted Consumption by Region (2027-2032)
- 6.3 North America
- 6.3.1 North America High Molecular Weight Polyester Resin Consumption Growth Rate by Country: 2021 VS 2025 VS 2032
- 6.3.2 North America High Molecular Weight Polyester Resin Consumption by Country (2021-2032)
- 6.3.3 United States
- 6.3.4 Canada
- 6.3.5 Mexico
- 6.4 Europe
- 6.4.1 Europe High Molecular Weight Polyester Resin Consumption Growth Rate by Country: 2021 VS 2025 VS 2032
- 6.4.2 Europe High Molecular Weight Polyester Resin Consumption by Country (2021-2032)
- 6.4.3 Germany
- 6.4.4 France
- 6.4.5 U.K.
- 6.4.6 Italy
- 6.4.7 Russia
- 6.4.8 Spain
- 6.4.9 Netherlands
- 6.4.10 Switzerland
- 6.4.11 Sweden
- 6.4.12 Poland
- 6.5 Asia Pacific
- 6.5.1 Asia Pacific High Molecular Weight Polyester Resin Consumption Growth Rate by Country: 2021 VS 2025 VS 2032
- 6.5.2 Asia Pacific High Molecular Weight Polyester Resin Consumption by Country (2021-2032)
- 6.5.3 China
- 6.5.4 Japan
- 6.5.5 South Korea
- 6.5.6 India
- 6.5.7 Australia
- 6.5.8 Taiwan
- 6.5.9 Southeast Asia
- 6.6 South America, Middle East & Africa
- 6.6.1 South America, Middle East & Africa High Molecular Weight Polyester Resin Consumption Growth Rate by Country: 2021 VS 2025 VS 2032
- 6.6.2 South America, Middle East & Africa High Molecular Weight Polyester Resin Consumption by Country (2021-2032)
- 6.6.3 Brazil
- 6.6.4 Argentina
- 6.6.5 Chile
- 6.6.6 Turkey
- 6.6.7 GCC Countries
7 Segment by Type
- 7.1 Global High Molecular Weight Polyester Resin Production by Type (2021-2032)
- 7.1.1 Global High Molecular Weight Polyester Resin Production by Type (2021-2032) & (tons)
- 7.1.2 Global High Molecular Weight Polyester Resin Production Market Share by Type (2021-2032)
- 7.2 Global High Molecular Weight Polyester Resin Production Value by Type (2021-2032)
- 7.2.1 Global High Molecular Weight Polyester Resin Production Value by Type (2021-2032) & (US$ Million)
- 7.2.2 Global High Molecular Weight Polyester Resin Production Value Market Share by Type (2021-2032)
- 7.3 Global High Molecular Weight Polyester Resin Price by Type (2021-2032)
8 Segment by Application
- 8.1 Global High Molecular Weight Polyester Resin Production by Application (2021-2032)
- 8.1.1 Global High Molecular Weight Polyester Resin Production by Application (2021-2032) & (tons)
- 8.1.2 Global High Molecular Weight Polyester Resin Production Market Share by Application (2021-2032)
- 8.2 Global High Molecular Weight Polyester Resin Production Value by Application (2021-2032)
- 8.2.1 Global High Molecular Weight Polyester Resin Production Value by Application (2021-2032) & (US$ Million)
- 8.2.2 Global High Molecular Weight Polyester Resin Production Value Market Share by Application (2021-2032)
- 8.3 Global High Molecular Weight Polyester Resin Price by Application (2021-2032)
9 Value Chain and Sales Channels Analysis of the Market
- 9.1 High Molecular Weight Polyester Resin Value Chain Analysis
- 9.1.1 High Molecular Weight Polyester Resin Key Raw Materials
- 9.1.2 Raw Materials Key Suppliers
- 9.1.3 High Molecular Weight Polyester Resin Production Mode & Process
- 9.2 High Molecular Weight Polyester Resin Sales Channels Analysis
- 9.2.1 Direct Comparison with Distribution Share
- 9.2.2 High Molecular Weight Polyester Resin Distributors
- 9.2.3 High Molecular Weight Polyester Resin Customers
10 Global High Molecular Weight Polyester Resin Analyzing Market Dynamics
- 10.1 High Molecular Weight Polyester Resin Industry Trends
- 10.2 High Molecular Weight Polyester Resin Industry Drivers
- 10.3 High Molecular Weight Polyester Resin Industry Opportunities and Challenges
- 10.4 High Molecular Weight Polyester Resin Industry Restraints
11 Report Conclusion
12 Disclaimer
GET THE RESEARCH
Choose your license.
Choose who needs access.
All options are for this report and research series.
PDF by email within 3–5 working days after payment confirmation.
Talk to an analyst