APO RESEARCH · REPORT
Foodservice Packaging
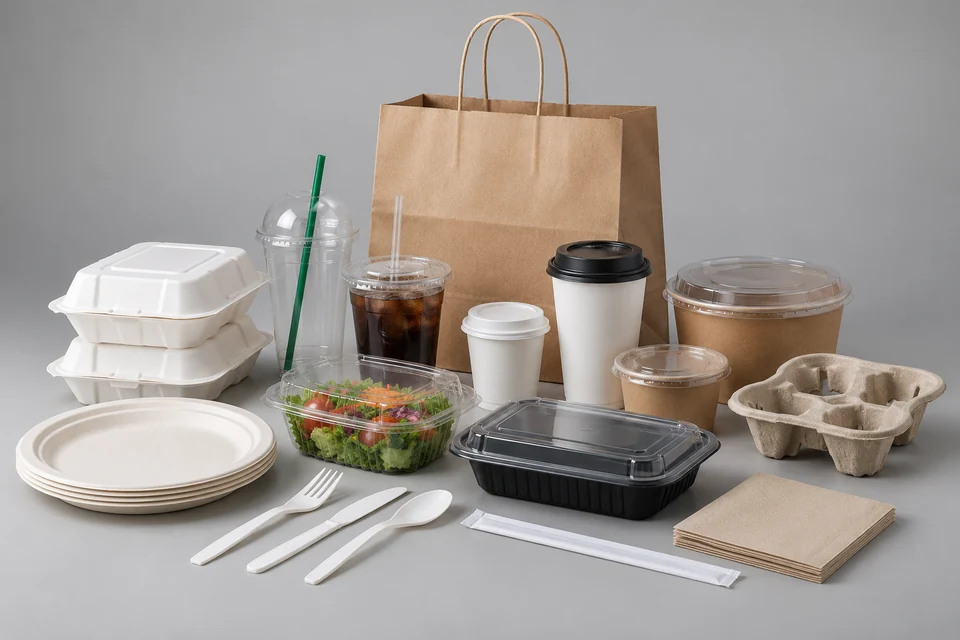
Foodservice packaging primarily includes single-use products such as cups (beverage and portion), plates, platters, bowls, trays, beverage carriers, bags (single portion and carry-out), containers, lids and domes, wraps, straws, cutlery and utensils for the service and/or packaging of prepared foods and beverages in foodservice establishments.
Product & engineering
Understand the product.
Foodservice packaging primarily includes single-use products such as cups (beverage and portion), plates, platters, bowls, trays, beverage carriers, bags (single portion and carry-out), containers, lids and domes, wraps, straws, cutlery and utensils for the service and/or packaging of prepared foods and beverages in foodservice establishments.
Today’s foodservice packaging choices include the more traditional Styrofoam and plastic options but also an array of new environmentally friendly choices including those made of paper, bagasse, cornstarch, and molded fiber. Foodservice packaging is largely, but not exclusively, made from recyclable paper, card and plastic.
The most commonly used plastics in foodservice packaging are polyethylene terephthalate (PET), recycled polyethylene terephthalate (RPET), polypropylene (PP), polystyrene (PS), expanded polystyrene (EPS) and high density [polyethylene (HDPE).
If 2023 was marked by a noticeable slowdown due to uncertainty, 2024 has been about the need for speed. The pressures weighing on the foodservice packaging industry have influenced this year's trends. Sustainability and the principles of sustainability in packaging have progressed from being a trend to a part of everyday business. The new trend appears to be the growing sense of urgency around packaging sustainability and the justification or rationalization of choices made in this space. Striving for sustainable packaging has gone beyond a "nice to have" to a required, if not now regulated, part of doing business. New legislation is creating added pressure across the industry and accelerating changes that demand careful planning and realistic timelines.
Considering the drive toward new and innovative materials and products, the pressure isn't all bad. These innovations help sustainability goals look new and fresh, all with performance attributes that help keep items at temperature and last longer. Notable changes include new coatings for fiber items that allow for reheating in the container and shifting away from color additives in favor of "natural" colored resin to help with end-of-life recyclability. The use of post-consumer recycled content also continues to grow in part due to customer commitments and the need to meet regulatory requirements. While this is a complex issue, especially regarding food contact packaging, we don't expect this trend to slow down any time soon.
Packaging materials are also receiving attention based on legislative and regulatory changes. As extended producer responsibility laws are implemented in several U.S. states, both foodservice operators and packaging manufacturers are left dealing with confusing and often conflicting approaches and targets. It may not be widespread, but we are seeing a greater focus on reusable items for dining at restaurants, event venues and school foodservice operations that may be tied to regulatory pressures and customer demand.
Adding to the pressure is the sliding scale of potential consequences around packaging decisions. Do companies switch portfolios from paper to plastics, plastics to paper, look at composability, recyclability or all of the above? Which attributes become the most important when selecting packaging that has to perform at an acceptable price point in a down market?
This year, a new standout for the industry was the number of mentions related to increased imports. From finished goods across multiple substrates to a rise in imported machinery, much of the U.S. and Canadian marketplace is thinking about this. A rise in imports has placed increased pressure on the industry to compete with both imported products and equipment. We also heard anecdotes about the rise in imported machinery leading to lower costs and shorter lead times for domestic equipment.
It's also important to mention the continued trend in mergers, acquisitions and consolidation that has led to tighter competition in the industry.
According to APO Research, the global Foodservice Packaging market was valued at US$ 62.21 billion in 2023 and is anticipated to reach US$ 93.49 billion by 2030, witnessing a CAGR of 7.36% from 2024 to 2030.
North American market for Foodservice Packaging is estimated to increase from $ 25.77 billion in 2024 to $ 41.48 billion by 2030, at a CAGR of 8.25 % from 2024 through 2030.
Asia-Pacific market for Foodservice Packaging is estimated to increase from $ 14.95 billion in 2024 to $ 22.47 million by 2030, at a CAGR of 7.03 % from 2024 through 2030.
The global market for Foodservice Packaging in Take Away/Delivery is estimated to increase from $ 23.53 billion in 2024 to $ 36.35 billion by 2030, at a CAGR of 7.52% from 2024 through 2030.
The major global companies of Foodservice Packaging include Graphic Packaging, Genpak, Sabert, Dart Container, Georgia-Pacific, Anchor Packaging, Pactiv Evergreen, D&W Fine Pack, and Berry Global. In 2023, the world's top three vendors accounted for approximately 16% of the revenue.
Packaging performance arises from the material, converted geometry, closure and filling or handling process. Material shipments, empty packs and filled-product sales are different objects and must be measured separately.
What turns activity into demand
Accepted filled packs create packaging demand through material per pack, converting yield and filling losses. The package, packaging material and the product it contains are different transaction objects.
The commercial boundary
For Foodservice Packaging, distinguish the supplied product from its inputs and the complete application. Report types and applications may overlap; retain the selected edition's product definition, geography, period, unit and transaction basis when comparing estimates.
Which conditions determine usable foodservice packaging performance?
Foodservice packaging primarily includes single-use products such as cups (beverage and portion), plates, platters, bowls, trays, beverage carriers, bags (single portion and carry-out), containers, lids and domes, wraps, straws, cutlery and utensils for the service and/or packaging of prepared foods and beverages in foodservice establishments. Verify barrier, sealing and mechanical requirements against the specified contents and handling duty. Relate accepted pack count to material intensity, converting yield and line loss; a material name alone does not establish pack performance.
Selected research
Industry Research
Foodservice Packaging Industry Research Report 2026
Market perspective
Foodservice packaging primarily includes single-use products such as cups (beverage and portion), plates, platters, bowls, trays, beverage carriers, bags (single portion and carry-out), containers, lids and domes, wraps, straws, cutlery and utensils for the service and/or packaging of prepared foods and beverages in foodservice establishments.
Today’s foodservice packaging choices include the more traditional Styrofoam and plastic options but also an array of new environmentally friendly choices including those made of paper, bagasse, cornstarch, and molded fiber. Foodservice packaging is largely, but not exclusively, made from recyclable paper, card and plastic.
The most commonly used plastics in foodservice packaging are polyethylene terephthalate (PET), recycled polyethylene terephthalate (RPET), polypropylene (PP), polystyrene (PS), expanded polystyrene (EPS) and high density [polyethylene (HDPE).
Read the full market overview
If 2023 was marked by a noticeable slowdown due to uncertainty, 2024 has been about the need for speed. The pressures weighing on the foodservice packaging industry have influenced this year's trends. Sustainability and the principles of sustainability in packaging have progressed from being a trend to a part of everyday business. The new trend appears to be the growing sense of urgency around packaging sustainability and the justification or rationalization of choices made in this space. Striving for sustainable packaging has gone beyond a "nice to have" to a required, if not now regulated, part of doing business. New legislation is creating added pressure across the industry and accelerating changes that demand careful planning and realistic timelines.
Considering the drive toward new and innovative materials and products, the pressure isn't all bad. These innovations help sustainability goals look new and fresh, all with performance attributes that help keep items at temperature and last longer. Notable changes include new coatings for fiber items that allow for reheating in the container and shifting away from color additives in favor of "natural" colored resin to help with end-of-life recyclability. The use of post-consumer recycled content also continues to grow in part due to customer commitments and the need to meet regulatory requirements. While this is a complex issue, especially regarding food contact packaging, we don't expect this trend to slow down any time soon.
Packaging materials are also receiving attention based on legislative and regulatory changes. As extended producer responsibility laws are implemented in several U.S. states, both foodservice operators and packaging manufacturers are left dealing with confusing and often conflicting approaches and targets. It may not be widespread, but we are seeing a greater focus on reusable items for dining at restaurants, event venues and school foodservice operations that may be tied to regulatory pressures and customer demand.
Adding to the pressure is the sliding scale of potential consequences around packaging decisions. Do companies switch portfolios from paper to plastics, plastics to paper, look at composability, recyclability or all of the above? Which attributes become the most important when selecting packaging that has to perform at an acceptable price point in a down market?
This year, a new standout for the industry was the number of mentions related to increased imports. From finished goods across multiple substrates to a rise in imported machinery, much of the U.S. and Canadian marketplace is thinking about this. A rise in imports has placed increased pressure on the industry to compete with both imported products and equipment. We also heard anecdotes about the rise in imported machinery leading to lower costs and shorter lead times for domestic equipment.
It's also important to mention the continued trend in mergers, acquisitions and consolidation that has led to tighter competition in the industry.
According to APO Research, the global Foodservice Packaging market was valued at US$ 62.21 billion in 2023 and is anticipated to reach US$ 93.49 billion by 2030, witnessing a CAGR of 7.36% from 2024 to 2030.
North American market for Foodservice Packaging is estimated to increase from $ 25.77 billion in 2024 to $ 41.48 billion by 2030, at a CAGR of 8.25 % from 2024 through 2030.
Asia-Pacific market for Foodservice Packaging is estimated to increase from $ 14.95 billion in 2024 to $ 22.47 million by 2030, at a CAGR of 7.03 % from 2024 through 2030.
The global market for Foodservice Packaging in Take Away/Delivery is estimated to increase from $ 23.53 billion in 2024 to $ 36.35 billion by 2030, at a CAGR of 7.52% from 2024 through 2030.
The major global companies of Foodservice Packaging include Graphic Packaging, Genpak, Sabert, Dart Container, Georgia-Pacific, Anchor Packaging, Pactiv Evergreen, D&W Fine Pack, and Berry Global. In 2023, the world's top three vendors accounted for approximately 16% of the revenue.
The global Foodservice Packaging market was valued at US$ million in 2025 and is projected to reach US$ million by 2032, implying a CAGR of % over 2026–2032.
North America: the Foodservice Packaging market is projected to increase from US$ million in 2026 to US$ million by 2032, reflecting a CAGR of % over 2026–2032. Europe: the Foodservice Packaging market is projected to rise from US$ million in 2026 to US$ million by 2032, registering a CAGR of % over 2026–2032. Asia Pacific: the Foodservice Packaging market is expected to grow from US$ million in 2026 to US$ million by 2032, at a CAGR of % over 2026–2032. Leading global service providers of Foodservice Packaging include Novolex, Dart Container, Huhtamaki, Pactiv Evergreen, Graphic Packaging, Sabert, Klöckner Pentaplast, WinCup and Amcor, among others; in 2025, the top three vendors together accounted for approximately % of global revenue.
Report Scope
This report quantifies the global Foodservice Packaging market in terms of revenue (US$ million) and, where applicable, service volume (k units), using 2024 as the base year and providing annual historical and forecast data for 2021–2032.
It standardizes definitions of service Types and end-use Applications, harmonizes provider attribution, and delivers comparable time series by company, Type, Application, and region or country, including indicative price bands (US$/k units) and concentration ratios (CR5/CR10). Outputs are intended to support service design, budgeting, capacity planning, and benchmarking for providers, platforms, channel partners, and investors; the report also reviews technology shifts and notable service innovations relevant to Foodservice Packaging.
Key Companies & Market Share Insights
This section profiles leading service providers with 2021–2025 results and a 2026–2032 outlook—covering revenue, market share, price bands, service portfolio and client mix, regional and channel mix, and key developments (M&A, network expansion, certifications). It also provides global revenue, average price, and—where applicable—volume metrics by provider, and calculates CR5/CR10 and rank changes to support comparative benchmarking.
Foodservice Packaging Market by Company
Novolex
Dart Container
Huhtamaki
Pactiv Evergreen
Graphic Packaging
Sabert
Klöckner Pentaplast
WinCup
Amcor
Genpak
D&W Fine Pack
Anchor Packaging
WestRock
Coveris
Cascades
Berry Global
Georgia-Pacific
Southern Champion Tray
Fuling Technology
Hefei Hengxin Life Science
Ningbo Homelink Eco-iTech
Zhejiang Pando Ep Technology
King Yuan Fu Packaging
CP Flexible Packaging
Fujian Nanwang
Foodservice Packaging Segment by Type
Flexible Packaging
Rigid Packaging
Paper & Paperboard
Others
Foodservice Packaging Segment by Application
Take Away/Delivery
Restaurants
Institutional Catering
HMR (Hotel Motel Restaurant)
Other
Foodservice Packaging Segment by Region
North America
United States
Canada
Mexico
Europe
Germany
France
U.K.
Italy
Spain
Russia
Netherlands
Nordic Countries
Asia-Pacific
China
Japan
South Korea
India
Australia
Taiwan
Southeast Asia
South America
Brazil
Argentina
Chile
Middle East & Africa
Saudi Arabia
Israel
United Arab Emirates
Turkey
Iran
Egypt
Key Drivers & Barriers
High-impact rendering factors and drivers have been studied in this report to aid the readers to understand the general development. Moreover, the report includes restraints and challenges that may act as stumbling blocks on the way of the players. This will assist the users to be attentive and make informed decisions related to business. Specialists have also laid their focus on the upcoming business prospects.
Reasons to Buy This Report
1. This report will help the readers to understand the competition within the industries and strategies for the competitive environment to enhance the potential profit. The report also focuses on the competitive landscape of the global Foodservice Packaging market, and introduces in detail the market share, industry ranking, competitor ecosystem, market performance, new product development, operation situation, expansion, and acquisition. etc. of the main players, which helps the readers to identify the main competitors and deeply understand the competition pattern of the market.
2. This report will help stakeholders to understand the global industry status and trends of Foodservice Packaging and provides them with information on key market drivers, restraints, challenges, and opportunities.
3. This report will help stakeholders to understand competitors better and gain more insights to strengthen their position in their businesses. The competitive landscape section includes the market share and rank (in volume and value), competitor ecosystem, new product development, expansion, and acquisition.
4. This report stays updated with novel technology integration, features, and the latest developments in the market
5. This report helps stakeholders to gain insights into which regions to target globally
6. This report helps stakeholders to gain insights into the end-user perception concerning the adoption of Foodservice Packaging.
7. This report helps stakeholders to identify some of the key players in the market and understand their valuable contribution.
Chapter Outline
Chapter 1: Research objectives, research methods, data sources, data cross-validation;
Chapter 2: Introduces the report scope of the report, executive summary of different market segments (product type, application, etc), including the market size of each market segment, future development potential, and so on. It offers a high-level view of the current state of the market and its likely evolution in the short to mid-term, and long term.
Chapter 3: Provides the analysis of various market segments product types, covering the market size and development potential of each market segment, to help readers find the blue ocean market in different market segments.
Chapter 4: Provides the analysis of various market segments application, covering the market size and development potential of each market segment, to help readers find the blue ocean market in different downstream markets.
Chapter 5: Introduces executive summary of global market size, regional market size, this section also introduces the market dynamics, latest developments of the market, the driving factors and restrictive factors of the market, the challenges and risks faced by companies in the industry, and the analysis of relevant policies in the industry.
Chapter 6: Detailed analysis of Foodservice Packaging companies’ competitive landscape, revenue market share, latest development plan, merger, and acquisition information, etc.
Chapter 7, 8, 9, 10, 11: North America, Europe, Asia Pacific, South America, Middle East and Africa segment by country. It provides a quantitative analysis of the market size and development potential of each region and its main countries and introduces the market development, future development prospects, market space, and capacity of each country in the world.
Chapter 12: Provides profiles of key players, introducing the basic situation of the main companies in the market in detail, including revenue, gross margin, product introduction, recent development, etc.
Chapter 13: The main points and conclusions of the report.
More report detail
Tables and figures
Scope & coverage.
Types
- Flexible Packaging
- Rigid Packaging
- Paper & Paperboard
- Others
Applications
- Take Away/Delivery
- Restaurants
- Institutional Catering
- HMR (Hotel Motel Restaurant)
- Other
Companies covered
- Novolex
- Dart Container
- Huhtamaki
- Pactiv Evergreen
- Graphic Packaging
- Sabert
- Klöckner Pentaplast
- WinCup
- Amcor
- Genpak
- D&W Fine Pack
- Anchor Packaging
- WestRock
- Coveris
- Cascades
- Berry Global
- Georgia-Pacific
- Southern Champion Tray
- Fuling Technology
- Hefei Hengxin Life Science
- Ningbo Homelink Eco-iTech
- Zhejiang Pando Ep Technology
- King Yuan Fu Packaging
- CP Flexible Packaging
- Fujian Nanwang
Inside the report.
1 Preface
- 1.1 Scope of Report
- 1.2 Reasons for Doing This Study
- 1.3 Research Methodology
- 1.4 Research Process
- 1.5 Data Source
- 1.5.1 Secondary Sources
- 1.5.2 Primary Sources
2 Market Overview
- 2.1 Product Definition
- 2.2 Foodservice Packaging by Type
- 2.2.1 Market Value Comparison by Type (2021 VS 2025 VS 2032)
- 2.2.2 Flexible Packaging
- 2.2.3 Rigid Packaging
- 2.2.4 Paper & Paperboard
- 2.2.5 Others
- 2.3 Foodservice Packaging by Application
- 2.3.1 Market Value Comparison by Application (2021 VS 2025 VS 2032)
- 2.3.2 Take Away/Delivery
- 2.3.3 Restaurants
- 2.3.4 Institutional Catering
- 2.3.5 HMR (Hotel Motel Restaurant)
- 2.3.6 Other
- 2.4 Assumptions and Limitations
3 Foodservice Packaging Breakdown Data by Type
- 3.1 Global Foodservice Packaging Historic Market Size by Type (2021-2026)
- 3.2 Global Foodservice Packaging Forecasted Market Size by Type (2027-2032)
4 Foodservice Packaging Breakdown Data by Application
- 4.1 Global Foodservice Packaging Historic Market Size by Application (2021-2026)
- 4.2 Global Foodservice Packaging Forecasted Market Size by Application (2027-2032)
5 Global Growth Trends
- 5.1 Global Foodservice Packaging Market Perspective (2021-2032)
- 5.2 Global Foodservice Packaging Growth Trends by Region
- 5.2.1 Global Foodservice Packaging Market Size by Region: 2021 VS 2025 VS 2032
- 5.2.2 Foodservice Packaging Historic Market Size by Region (2021-2026)
- 5.2.3 Foodservice Packaging Forecasted Market Size by Region (2027-2032)
- 5.3 Foodservice Packaging Market Dynamics
- 5.3.1 Foodservice Packaging Industry Trends
- 5.3.2 Foodservice Packaging Market Drivers
- 5.3.3 Foodservice Packaging Market Challenges
- 5.3.4 Foodservice Packaging Market Restraints
6 Market Competitive Landscape by Players
- 6.1 Global Top Foodservice Packaging Players by Revenue
- 6.1.1 Global Top Foodservice Packaging Players by Revenue (2021-2026)
- 6.1.2 Global Foodservice Packaging Revenue Market Share by Players (2021-2026)
- 6.2 Global Foodservice Packaging Industry Players Ranking, 2023 VS 2024 VS 2025
- 6.3 Global Key Players of Foodservice Packaging Head Office and Area Served
- 6.4 Global Foodservice Packaging Players, Product Type & Application
- 6.5 Global Foodservice Packaging Manufacturers Established Date
- 6.6 Global Foodservice Packaging Market CR5 and HHI
- 6.7 Global Players Mergers & Acquisition
7 North America
- 7.1 North America Foodservice Packaging Market Size (2021-2032)
- 7.2 North America Foodservice Packaging Market Growth Rate by Country: 2021 VS 2025 VS 2032
- 7.3 North America Foodservice Packaging Market Size by Country (2021-2026)
- 7.4 North America Foodservice Packaging Market Size by Country (2027-2032)
- 7.5 United States
- 7.5 United States
- 7.6 Canada
- 7.7 Mexico
8 Europe
- 8.1 Europe Foodservice Packaging Market Size (2021-2032)
- 8.2 Europe Foodservice Packaging Market Growth Rate by Country: 2021 VS 2025 VS 2032
- 8.3 Europe Foodservice Packaging Market Size by Country (2021-2026)
- 8.4 Europe Foodservice Packaging Market Size by Country (2027-2032)
- 8.5 Germany
- 8.6 France
- 8.7 U.K.
- 8.8 Italy
- 8.9 Spain
- 8.10 Russia
- 8.11 Netherlands
- 8.12 Nordic Countries
9 Asia-Pacific
- 9.1 Asia-Pacific Foodservice Packaging Market Size (2021-2032)
- 9.2 Asia-Pacific Foodservice Packaging Market Growth Rate by Country: 2021 VS 2025 VS 2032
- 9.3 Asia-Pacific Foodservice Packaging Market Size by Country (2021-2026)
- 9.4 Asia-Pacific Foodservice Packaging Market Size by Country (2027-2032)
- 9.5 China
- 9.6 Japan
- 9.7 South Korea
- 9.8 India
- 9.9 Australia
- 9.10 China Taiwan
- 9.11 Southeast Asia
10 South America
- 10.1 South America Foodservice Packaging Market Size (2021-2032)
- 10.2 South America Foodservice Packaging Market Growth Rate by Country: 2021 VS 2025 VS 2032
- 10.3 South America Foodservice Packaging Market Size by Country (2021-2026)
- 10.4 South America Foodservice Packaging Market Size by Country (2027-2032)
- 10.5 Brazil
- 10.6 Argentina
- 10.7 Chile
- 10.8 Colombia
- 10.9 Peru
11 Middle East & Africa
- 11.1 Middle East & Africa Foodservice Packaging Market Size (2021-2032)
- 11.2 Middle East & Africa Foodservice Packaging Market Growth Rate by Country: 2021 VS 2025 VS 2032
- 11.3 Middle East & Africa Foodservice Packaging Market Size by Country (2021-2026)
- 11.4 Middle East & Africa Foodservice Packaging Market Size by Country (2027-2032)
- 11.5 Saudi Arabia
- 11.6 Israel
- 11.7 United Arab Emirates
- 11.8 Turkey
- 11.9 Iran
- 11.10 Egypt
12 Players Profiled
- 12.1 Novolex
- 12.1.1 Novolex Company Information
- 12.1.2 Novolex Business Overview
- 12.1.3 Novolex Revenue in Foodservice Packaging Business (2021-2026)
- 12.1.4 Novolex Foodservice Packaging Product Portfolio
- 12.1.5 Novolex Recent Developments
- 12.2 Dart Container
- 12.2.1 Dart Container Company Information
- 12.2.2 Dart Container Business Overview
- 12.2.3 Dart Container Revenue in Foodservice Packaging Business (2021-2026)
- 12.2.4 Dart Container Foodservice Packaging Product Portfolio
- 12.2.5 Dart Container Recent Developments
- 12.3 Huhtamaki
- 12.3.1 Huhtamaki Company Information
- 12.3.2 Huhtamaki Business Overview
- 12.3.3 Huhtamaki Revenue in Foodservice Packaging Business (2021-2026)
- 12.3.4 Huhtamaki Foodservice Packaging Product Portfolio
- 12.3.5 Huhtamaki Recent Developments
- 12.4 Pactiv Evergreen
- 12.4.1 Pactiv Evergreen Company Information
- 12.4.2 Pactiv Evergreen Business Overview
- 12.4.3 Pactiv Evergreen Revenue in Foodservice Packaging Business (2021-2026)
- 12.4.4 Pactiv Evergreen Foodservice Packaging Product Portfolio
- 12.4.5 Pactiv Evergreen Recent Developments
- 12.5 Graphic Packaging
- 12.5.1 Graphic Packaging Company Information
- 12.5.2 Graphic Packaging Business Overview
- 12.5.3 Graphic Packaging Revenue in Foodservice Packaging Business (2021-2026)
- 12.5.4 Graphic Packaging Foodservice Packaging Product Portfolio
- 12.5.5 Graphic Packaging Recent Developments
- 12.6 Sabert
- 12.6.1 Sabert Company Information
- 12.6.2 Sabert Business Overview
- 12.6.3 Sabert Revenue in Foodservice Packaging Business (2021-2026)
- 12.6.4 Sabert Foodservice Packaging Product Portfolio
- 12.6.5 Sabert Recent Developments
- 12.7 Klöckner Pentaplast
- 12.7.1 Klöckner Pentaplast Company Information
- 12.7.2 Klöckner Pentaplast Business Overview
- 12.7.3 Klöckner Pentaplast Revenue in Foodservice Packaging Business (2021-2026)
- 12.7.4 Klöckner Pentaplast Foodservice Packaging Product Portfolio
- 12.7.5 Klöckner Pentaplast Recent Developments
- 12.8 WinCup
- 12.8.1 WinCup Company Information
- 12.8.2 WinCup Business Overview
- 12.8.3 WinCup Revenue in Foodservice Packaging Business (2021-2026)
- 12.8.4 WinCup Foodservice Packaging Product Portfolio
- 12.8.5 WinCup Recent Developments
- 12.9 Amcor
- 12.9.1 Amcor Company Information
- 12.9.2 Amcor Business Overview
- 12.9.3 Amcor Revenue in Foodservice Packaging Business (2021-2026)
- 12.9.4 Amcor Foodservice Packaging Product Portfolio
- 12.9.5 Amcor Recent Developments
- 12.10 Genpak
- 12.10.1 Genpak Company Information
- 12.10.2 Genpak Business Overview
- 12.10.3 Genpak Revenue in Foodservice Packaging Business (2021-2026)
- 12.10.4 Genpak Foodservice Packaging Product Portfolio
- 12.10.5 Genpak Recent Developments
- 12.11 D&W Fine Pack
- 12.11.1 D&W Fine Pack Company Information
- 12.11.2 D&W Fine Pack Business Overview
- 12.11.3 D&W Fine Pack Revenue in Foodservice Packaging Business (2021-2026)
- 12.11.4 D&W Fine Pack Foodservice Packaging Product Portfolio
- 12.11.5 D&W Fine Pack Recent Developments
- 12.12 Anchor Packaging
- 12.12.1 Anchor Packaging Company Information
- 12.12.2 Anchor Packaging Business Overview
- 12.12.3 Anchor Packaging Revenue in Foodservice Packaging Business (2021-2026)
- 12.12.4 Anchor Packaging Foodservice Packaging Product Portfolio
- 12.12.5 Anchor Packaging Recent Developments
- 12.13 WestRock
- 12.13.1 WestRock Company Information
- 12.13.2 WestRock Business Overview
- 12.13.3 WestRock Revenue in Foodservice Packaging Business (2021-2026)
- 12.13.4 WestRock Foodservice Packaging Product Portfolio
- 12.13.5 WestRock Recent Developments
- 12.14 Coveris
- 12.14.1 Coveris Company Information
- 12.14.2 Coveris Business Overview
- 12.14.3 Coveris Revenue in Foodservice Packaging Business (2021-2026)
- 12.14.4 Coveris Foodservice Packaging Product Portfolio
- 12.14.5 Coveris Recent Developments
- 12.15 Cascades
- 12.15.1 Cascades Company Information
- 12.15.2 Cascades Business Overview
- 12.15.3 Cascades Revenue in Foodservice Packaging Business (2021-2026)
- 12.15.4 Cascades Foodservice Packaging Product Portfolio
- 12.15.5 Cascades Recent Developments
- 12.16 Berry Global
- 12.16.1 Berry Global Company Information
- 12.16.2 Berry Global Business Overview
- 12.16.3 Berry Global Revenue in Foodservice Packaging Business (2021-2026)
- 12.16.4 Berry Global Foodservice Packaging Product Portfolio
- 12.16.5 Berry Global Recent Developments
- 12.17 Georgia-Pacific
- 12.17.1 Georgia-Pacific Company Information
- 12.17.2 Georgia-Pacific Business Overview
- 12.17.3 Georgia-Pacific Revenue in Foodservice Packaging Business (2021-2026)
- 12.17.4 Georgia-Pacific Foodservice Packaging Product Portfolio
- 12.17.5 Georgia-Pacific Recent Developments
- 12.18 Southern Champion Tray
- 12.18.1 Southern Champion Tray Company Information
- 12.18.2 Southern Champion Tray Business Overview
- 12.18.3 Southern Champion Tray Revenue in Foodservice Packaging Business (2021-2026)
- 12.18.4 Southern Champion Tray Foodservice Packaging Product Portfolio
- 12.18.5 Southern Champion Tray Recent Developments
- 12.19 Fuling Technology
- 12.19.1 Fuling Technology Company Information
- 12.19.2 Fuling Technology Business Overview
- 12.19.3 Fuling Technology Revenue in Foodservice Packaging Business (2021-2026)
- 12.19.4 Fuling Technology Foodservice Packaging Product Portfolio
- 12.19.5 Fuling Technology Recent Developments
- 12.20 Hefei Hengxin Life Science
- 12.20.1 Hefei Hengxin Life Science Company Information
- 12.20.2 Hefei Hengxin Life Science Business Overview
- 12.20.3 Hefei Hengxin Life Science Revenue in Foodservice Packaging Business (2021-2026)
- 12.20.4 Hefei Hengxin Life Science Foodservice Packaging Product Portfolio
- 12.20.5 Hefei Hengxin Life Science Recent Developments
- 12.21 Ningbo Homelink Eco-iTech
- 12.21.1 Ningbo Homelink Eco-iTech Company Information
- 12.21.2 Ningbo Homelink Eco-iTech Business Overview
- 12.21.3 Ningbo Homelink Eco-iTech Revenue in Foodservice Packaging Business (2021-2026)
- 12.21.4 Ningbo Homelink Eco-iTech Foodservice Packaging Product Portfolio
- 12.21.5 Ningbo Homelink Eco-iTech Recent Developments
- 12.22 Zhejiang Pando Ep Technology
- 12.22.1 Zhejiang Pando Ep Technology Company Information
- 12.22.2 Zhejiang Pando Ep Technology Business Overview
- 12.22.3 Zhejiang Pando Ep Technology Revenue in Foodservice Packaging Business (2021-2026)
- 12.22.4 Zhejiang Pando Ep Technology Foodservice Packaging Product Portfolio
- 12.22.5 Zhejiang Pando Ep Technology Recent Developments
- 12.23 King Yuan Fu Packaging
- 12.23.1 King Yuan Fu Packaging Company Information
- 12.23.2 King Yuan Fu Packaging Business Overview
- 12.23.3 King Yuan Fu Packaging Revenue in Foodservice Packaging Business (2021-2026)
- 12.23.4 King Yuan Fu Packaging Foodservice Packaging Product Portfolio
- 12.23.5 King Yuan Fu Packaging Recent Developments
- 12.24 CP Flexible Packaging
- 12.24.1 CP Flexible Packaging Company Information
- 12.24.2 CP Flexible Packaging Business Overview
- 12.24.3 CP Flexible Packaging Revenue in Foodservice Packaging Business (2021-2026)
- 12.24.4 CP Flexible Packaging Foodservice Packaging Product Portfolio
- 12.24.5 CP Flexible Packaging Recent Developments
- 12.25 Fujian Nanwang
- 12.25.1 Fujian Nanwang Company Information
- 12.25.2 Fujian Nanwang Business Overview
- 12.25.3 Fujian Nanwang Revenue in Foodservice Packaging Business (2021-2026)
- 12.25.4 Fujian Nanwang Foodservice Packaging Product Portfolio
- 12.25.5 Fujian Nanwang Recent Developments
13 Report Conclusion
14 Disclaimer
GET THE RESEARCH
Choose your license.
Choose who needs access.
All options are for this report and research series.
PDF by email within 3–5 working days after payment confirmation.
Talk to an analyst