APO RESEARCH · REPORT
Trading Card
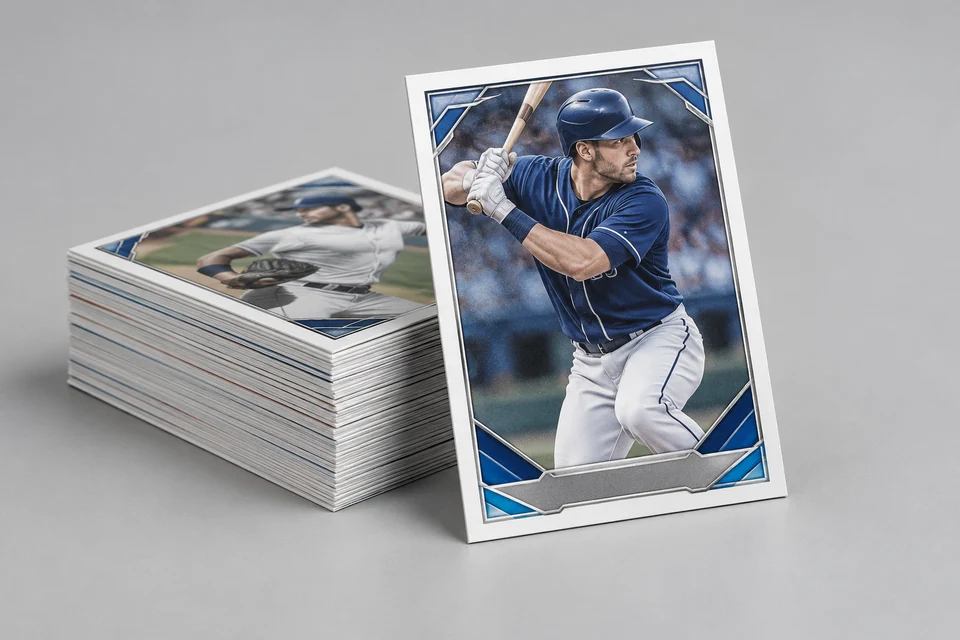
Trading cards are standardized collectible card products manufactured primarily from paperboard or other rigid printed substrates and issued in organized sets, packs, boxes, and special editions for collection, exchange, retail merchandising, and, in some product lines, structured gameplay.
Product & engineering
Understand the product.
Trading cards are standardized collectible card products manufactured primarily from paperboard or other rigid printed substrates and issued in organized sets, packs, boxes, and special editions for collection, exchange, retail merchandising, and, in some product lines, structured gameplay. The category spans sports cards, entertainment cards, character cards, game related cards, and event themed cards, with each card typically combining visual design and structured content such as player or character identity, team or franchise affiliation, statistics, abilities, rarity, serial numbering, memorabilia inserts, autograph authentication, or other edition specific attributes. Individual cards circulated outside sealed configurations are commonly traded and sold as singles. Although the category originated in sports collectibles, it has developed into a broader licensed and original content market that includes animation, comics, film, television, and trading card game ecosystems. From a commercial classification perspective, trading cards can be grouped into original design products built around proprietary concepts and licensed products based on established intellectual properties such as sports leagues, game franchises, film characters, and entertainment brands.
The United States trading card market has historically been anchored in sports culture, with baseball, basketball, and American football cards forming the core of the category. The origins of the market can be traced to the late nineteenth century, when tobacco companies used inserted cards as promotional items. Over more than a century of development, the US market evolved from a collectibles business into a more structured commercial ecosystem spanning card issuance, grading, collecting, secondary market trading, and auction activity. A defining feature of the modern US market is its high degree of financialization, as trading cards are widely treated not only as cultural memorabilia and hobby products, but also as assets with investment and resale potential. This dynamic has supported the emergence of a mature value chain in which brand owners, card issuers, grading companies, marketplaces, auction houses, and collectors each play a distinct economic role.
Japan followed a different path, with the trading card industry centered more strongly on trading card games and character driven intellectual property, particularly under the influence of anime, manga, and game culture. Representative products such as Yu Gi Oh and Pokémon became cultural landmarks that linked card ownership to entertainment consumption, organized play, and community participation. The Japanese market experienced two major growth waves. The first took shape in the 1990s, when the rapid expansion of anime and game related franchises drove the establishment of broad offline retail distribution, tournament infrastructure, and player communities. The second gained momentum in the 2010s, when an aging consumer base with greater purchasing power, combined with growing participation from adults outside the traditional player population, pushed the category further toward premium collecting and investment oriented demand. As a result, Japan developed a market structure in which gameplay, fandom, retail community, and collectible value remain closely interconnected.
The finished product is defined by the task it performs, its construction and the user interface. Accessories, complete products and repair or subscription services can share a use case while remaining different transaction objects.
What turns activity into demand
Active users, fitted products and replacement cycles connect use to purchases. Accessories, the main product and paid services may be related but should retain distinct transaction boundaries.
The commercial boundary
For Trading Card, distinguish the supplied product from its inputs and the complete application. Report types and applications may overlap; retain the selected edition's product definition, geography, period, unit and transaction basis when comparing estimates.
What defines the supplied trading card offering?
Trading cards are standardized collectible card products manufactured primarily from paperboard or other rigid printed substrates and issued in organized sets, packs, boxes, and special editions for collection, exchange, retail merchandising, and, in some product lines, structured gameplay. Check the actual load, fit, material, service life and interface requirements. Product count, installed stock and replacement activity should be reconciled; a visual resemblance or marketing class does not make products technically equivalent.
Selected research
Industry Research
Trading Card Industry Research Report 2026
Market perspective
Trading cards are standardized collectible card products manufactured primarily from paperboard or other rigid printed substrates and issued in organized sets, packs, boxes, and special editions for collection, exchange, retail merchandising, and, in some product lines, structured gameplay. The category spans sports cards, entertainment cards, character cards, game related cards, and event themed cards, with each card typically combining visual design and structured content such as player or character identity, team or franchise affiliation, statistics, abilities, rarity, serial numbering, memorabilia inserts, autograph authentication, or other edition specific attributes. Individual cards circulated outside sealed configurations are commonly traded and sold as singles. Although the category originated in sports collectibles, it has developed into a broader licensed and original content market that includes animation, comics, film, television, and trading card game ecosystems. From a commercial classification perspective, trading cards can be grouped into original design products built around proprietary concepts and licensed products based on established intellectual properties such as sports leagues, game franchises, film characters, and entertainment brands.
The United States trading card market has historically been anchored in sports culture, with baseball, basketball, and American football cards forming the core of the category. The origins of the market can be traced to the late nineteenth century, when tobacco companies used inserted cards as promotional items. Over more than a century of development, the US market evolved from a collectibles business into a more structured commercial ecosystem spanning card issuance, grading, collecting, secondary market trading, and auction activity. A defining feature of the modern US market is its high degree of financialization, as trading cards are widely treated not only as cultural memorabilia and hobby products, but also as assets with investment and resale potential. This dynamic has supported the emergence of a mature value chain in which brand owners, card issuers, grading companies, marketplaces, auction houses, and collectors each play a distinct economic role.
Japan followed a different path, with the trading card industry centered more strongly on trading card games and character driven intellectual property, particularly under the influence of anime, manga, and game culture. Representative products such as Yu Gi Oh and Pokémon became cultural landmarks that linked card ownership to entertainment consumption, organized play, and community participation. The Japanese market experienced two major growth waves. The first took shape in the 1990s, when the rapid expansion of anime and game related franchises drove the establishment of broad offline retail distribution, tournament infrastructure, and player communities. The second gained momentum in the 2010s, when an aging consumer base with greater purchasing power, combined with growing participation from adults outside the traditional player population, pushed the category further toward premium collecting and investment oriented demand. As a result, Japan developed a market structure in which gameplay, fandom, retail community, and collectible value remain closely interconnected.
Read the full market overview
The global Trading Card market is entering a phase of sustained scale expansion in which category penetration, release intensity, collector participation, and product mix are all contributing to growth. Global market value increased from US$ 6,367.1 million in 2021 to US$ 12,575.3 million in 2025 and is estimated at US$ 14,598.9 million in 2026. The market is projected to reach US$ 29,904.6 million by 2032, implying a CAGR of 12.69% from 2026 to 2032. The expansion profile is supported by both commercial volume growth and higher realized value. Directional unit volume rises from 71,475 M units in 2025 to 80,433 M units in 2026 and further to 144,948 M units in 2032, while blended ASP increases from 175.9 to 181.5 and then to 206.3 US dollars per K unit over the same period. Growth therefore reflects a combination of broader market participation, stronger monetization, and continued premiumization across major card categories.
By Type, Gaming or TCG Cards remain the economic center of the industry, supported by organized play, repeat booster consumption, long product life cycles, and durable IP ecosystems. Segment revenue rises from US$ 8,181.2 million in 2026 to US$ 15,819.7 million in 2032, although its revenue share eases from 60.15% in 2021 to 56.04% in 2026 and 52.90% in 2032 as the market broadens. Sports Trading Cards remain structurally important and comparatively resilient in value, increasing from US$ 3,788.4 million in 2026 to US$ 7,790.5 million in 2032, with share broadly stable at about one quarter of the market and with the highest blended ASP among the three major categories. Non Sports Cards represent the strongest share gain story in the forecast, rising from US$ 2,629.3 million in 2026 to US$ 6,294.4 million in 2032, while share expands from 18.01% to 21.05%. The resulting market structure is one in which gaming preserves scale leadership, sports preserves pricing strength, and non sports captures the fastest structural broadening under the support of entertainment, anime, and character driven IP.
Channel development shows a clear shift in monetization toward digital commerce, even as physical retail and hobby infrastructure remain central to discovery, play, and collector engagement. Offline Sales still account for the larger channel base, with revenue of US$ 10,472.2 million in 2026 and US$ 18,727.5 million by 2032, though channel share declines from 79.55% in 2021 to 71.73% in 2026 and 62.62% in 2032. Online Sales rise from US$ 4,126.7 million in 2026 to US$ 11,177.1 million in 2032, with share moving from 20.45% in 2021 to 28.27% in 2026 and 37.38% in 2032. This points to a market in which ecommerce, marketplace liquidity, livestream and platform based conversion, and wider cross market accessibility are taking a larger share of revenue formation, while offline stores, hobby shops, and event venues continue to anchor community, launch execution, and organized participation.
Regional performance indicates a clear divergence between value concentration and volume concentration. Europe is the largest value market in the report framework, reaching US$ 7,062.3 million in 2026 and projected to expand to US$ 14,864.9 million by 2032. North America follows at US$ 4,698.5 million in 2026 and US$ 9,218.4 million in 2032, supported by a mature sports collectibles culture, strong grading intensity, and deep licensed brand monetization. Asia Pacific is smaller by reported value, at US$ 1,897.9 million in 2026 and US$ 3,745.3 million in 2032, but it is the dominant region in directional unit terms, accounting for 44,250 M units in 2026 and 82,217 M units in 2032, or roughly 55% to 57% of global unit volume through the forecast horizon. This combination suggests that Europe and North America capture a larger share of value through stronger spending depth and price realization, while Asia Pacific carries the broadest physical scale in card circulation and mass market sell through. Latin America and Middle East and Africa remain smaller in absolute size, though both continue to post double digit growth through 2032.
Report Scope
This report quantifies the global Trading Card market in terms of revenue (US$ million) and, where applicable, service volume (k units), using 2024 as the base year and providing annual historical and forecast data for 2021–2032.
It standardizes definitions of service Types and end-use Applications, harmonizes provider attribution, and delivers comparable time series by company, Type, Application, and region or country, including indicative price bands (US$/k units) and concentration ratios (CR5/CR10). Outputs are intended to support service design, budgeting, capacity planning, and benchmarking for providers, platforms, channel partners, and investors; the report also reviews technology shifts and notable service innovations relevant to Trading Card.
Key Companies & Market Share Insights
This section profiles leading service providers with 2021–2025 results and a 2026–2032 outlook—covering revenue, market share, price bands, service portfolio and client mix, regional and channel mix, and key developments (M&A, network expansion, certifications). It also provides global revenue, average price, and—where applicable—volume metrics by provider, and calculates CR5/CR10 and rank changes to support comparative benchmarking.
Trading Card Market by Company
Pokémon
Fanatics
Wizards of the Coast
Kayou
Konami
Bandai Namco
Panini
Suplay
Ravensburger
The Upper Deck
Bushiroad
Jason Anime
Tomy Company
Trading Card Segment by Type
Sports Trading Cards
Gaming or TCG Cards
Non Sports Cards
Others
Trading Card Segment by Application
Online Sales
Offline Sales
Trading Card Segment by Region
North America
United States
Canada
Mexico
Europe
Germany
France
U.K.
Italy
Spain
Russia
Netherlands
Nordic Countries
Asia-Pacific
China
Japan
South Korea
India
Australia
Taiwan
Southeast Asia
South America
Brazil
Argentina
Chile
Colombia
Middle East & Africa
Saudi Arabia
Israel
United Arab Emirates
Turkey
Iran
Egypt
Key Drivers & Barriers
High-impact rendering factors and drivers have been studied in this report to aid the readers to understand the general development. Moreover, the report includes restraints and challenges that may act as stumbling blocks on the way of the players. This will assist the users to be attentive and make informed decisions related to business. Specialists have also laid their focus on the upcoming business prospects.
Reasons to Buy This Report
1. This report will help the readers to understand the competition within the industries and strategies for the competitive environment to enhance the potential profit. The report also focuses on the competitive landscape of the global Trading Card market, and introduces in detail the market share, industry ranking, competitor ecosystem, market performance, new product development, operation situation, expansion, and acquisition. etc. of the main players, which helps the readers to identify the main competitors and deeply understand the competition pattern of the market.
2. This report will help stakeholders to understand the global industry status and trends of Trading Card and provides them with information on key market drivers, restraints, challenges, and opportunities.
3. This report will help stakeholders to understand competitors better and gain more insights to strengthen their position in their businesses. The competitive landscape section includes the market share and rank (in volume and value), competitor ecosystem, new product development, expansion, and acquisition.
4. This report stays updated with novel technology integration, features, and the latest developments in the market
5. This report helps stakeholders to gain insights into which regions to target globally
6. This report helps stakeholders to gain insights into the end-user perception concerning the adoption of Trading Card.
7. This report helps stakeholders to identify some of the key players in the market and understand their valuable contribution.
Chapter Outline
Chapter 1: Research objectives, research methods, data sources, data cross-validation;
Chapter 2: Introduces the report scope of the report, executive summary of different market segments (product type, application, etc), including the market size of each market segment, future development potential, and so on. It offers a high-level view of the current state of the market and its likely evolution in the short to mid-term, and long term.
Chapter 3: Provides the analysis of various market segments product types, covering the market size and development potential of each market segment, to help readers find the blue ocean market in different market segments.
Chapter 4: Provides the analysis of various market segments application, covering the market size and development potential of each market segment, to help readers find the blue ocean market in different downstream markets.
Chapter 5: Introduces executive summary of global market size, regional market size, this section also introduces the market dynamics, latest developments of the market, the driving factors and restrictive factors of the market, the challenges and risks faced by companies in the industry, and the analysis of relevant policies in the industry.
Chapter 6: Detailed analysis of Trading Card companies’ competitive landscape, revenue market share, latest development plan, merger, and acquisition information, etc.
Chapter 7, 8, 9, 10, 11: North America, Europe, Asia Pacific, South America, Middle East and Africa segment by country. It provides a quantitative analysis of the market size and development potential of each region and its main countries and introduces the market development, future development prospects, market space, and capacity of each country in the world.
Chapter 12: Provides profiles of key players, introducing the basic situation of the main companies in the market in detail, including revenue, gross margin, product introduction, recent development, etc.
Chapter 13: The main points and conclusions of the report.
More report detail
Tables and figures
Scope & coverage.
Types
- Sports Trading Cards
- Gaming or TCG Cards
- Non Sports Cards
- Others
Applications
- Online Sales
- Offline Sales
Companies covered
- Pokémon
- Fanatics
- Wizards of the Coast
- Kayou
- Konami
- Bandai Namco
- Panini
- Suplay
- Ravensburger
- The Upper Deck
- Bushiroad
- Jason Anime
- Tomy Company
Inside the report.
1 Preface
- 1.1 Scope of Report
- 1.2 Reasons for Doing This Study
- 1.3 Research Methodology
- 1.4 Research Process
- 1.5 Data Source
- 1.5.1 Secondary Sources
- 1.5.2 Primary Sources
2 Market Overview
- 2.1 Product Definition
- 2.2 Trading Card by Type
- 2.2.1 Market Value Comparison by Type (2021 VS 2025 VS 2032)
- 2.2.2 Sports Trading Cards
- 2.2.3 Gaming or TCG Cards
- 2.2.4 Non Sports Cards
- 2.2.5 Others
- 2.3 Trading Card by Application
- 2.3.1 Market Value Comparison by Application (2021 VS 2025 VS 2032)
- 2.3.2 Online Sales
- 2.3.3 Offline Sales
- 2.4 Assumptions and Limitations
3 Trading Card Breakdown Data by Type
- 3.1 Global Trading Card Historic Market Size by Type (2021-2026)
- 3.2 Global Trading Card Forecasted Market Size by Type (2027-2032)
4 Trading Card Breakdown Data by Application
- 4.1 Global Trading Card Historic Market Size by Application (2021-2026)
- 4.2 Global Trading Card Forecasted Market Size by Application (2027-2032)
5 Global Growth Trends
- 5.1 Global Trading Card Market Perspective (2021-2032)
- 5.2 Global Trading Card Growth Trends by Region
- 5.2.1 Global Trading Card Market Size by Region: 2021 VS 2025 VS 2032
- 5.2.2 Trading Card Historic Market Size by Region (2021-2026)
- 5.2.3 Trading Card Forecasted Market Size by Region (2027-2032)
- 5.3 Trading Card Market Dynamics
- 5.3.1 Trading Card Industry Trends
- 5.3.2 Trading Card Market Drivers
- 5.3.3 Trading Card Market Challenges
- 5.3.4 Trading Card Market Restraints
6 Market Competitive Landscape by Players
- 6.1 Global Top Trading Card Players by Revenue
- 6.1.1 Global Top Trading Card Players by Revenue (2021-2026)
- 6.1.2 Global Trading Card Revenue Market Share by Players (2021-2026)
- 6.2 Global Trading Card Industry Players Ranking, 2023 VS 2024 VS 2025
- 6.3 Global Key Players of Trading Card Head Office and Area Served
- 6.4 Global Trading Card Players, Product Type & Application
- 6.5 Global Trading Card Manufacturers Established Date
- 6.6 Global Trading Card Market CR5 and HHI
- 6.7 Global Players Mergers & Acquisition
7 North America
- 7.1 North America Trading Card Market Size (2021-2032)
- 7.2 North America Trading Card Market Growth Rate by Country: 2021 VS 2025 VS 2032
- 7.3 North America Trading Card Market Size by Country (2021-2026)
- 7.4 North America Trading Card Market Size by Country (2027-2032)
- 7.5 United States
- 7.5 United States
- 7.6 Canada
- 7.7 Mexico
8 Europe
- 8.1 Europe Trading Card Market Size (2021-2032)
- 8.2 Europe Trading Card Market Growth Rate by Country: 2021 VS 2025 VS 2032
- 8.3 Europe Trading Card Market Size by Country (2021-2026)
- 8.4 Europe Trading Card Market Size by Country (2027-2032)
- 8.5 Germany
- 8.6 France
- 8.7 U.K.
- 8.8 Italy
- 8.9 Spain
- 8.10 Russia
- 8.11 Netherlands
- 8.12 Nordic Countries
9 Asia-Pacific
- 9.1 Asia-Pacific Trading Card Market Size (2021-2032)
- 9.2 Asia-Pacific Trading Card Market Growth Rate by Country: 2021 VS 2025 VS 2032
- 9.3 Asia-Pacific Trading Card Market Size by Country (2021-2026)
- 9.4 Asia-Pacific Trading Card Market Size by Country (2027-2032)
- 9.5 China
- 9.6 Japan
- 9.7 South Korea
- 9.8 India
- 9.9 Australia
- 9.10 China Taiwan
- 9.11 Southeast Asia
10 South America
- 10.1 South America Trading Card Market Size (2021-2032)
- 10.2 South America Trading Card Market Growth Rate by Country: 2021 VS 2025 VS 2032
- 10.3 South America Trading Card Market Size by Country (2021-2026)
- 10.4 South America Trading Card Market Size by Country (2027-2032)
- 10.5 Brazil
- 10.6 Argentina
- 10.7 Chile
- 10.8 Colombia
- 10.9 Peru
11 Middle East & Africa
- 11.1 Middle East & Africa Trading Card Market Size (2021-2032)
- 11.2 Middle East & Africa Trading Card Market Growth Rate by Country: 2021 VS 2025 VS 2032
- 11.3 Middle East & Africa Trading Card Market Size by Country (2021-2026)
- 11.4 Middle East & Africa Trading Card Market Size by Country (2027-2032)
- 11.5 Saudi Arabia
- 11.6 Israel
- 11.7 United Arab Emirates
- 11.8 Turkey
- 11.9 Iran
- 11.10 Egypt
12 Players Profiled
- 12.1 Pokémon
- 12.1.1 Pokémon Company Information
- 12.1.2 Pokémon Business Overview
- 12.1.3 Pokémon Revenue in Trading Card Business (2021-2026)
- 12.1.4 Pokémon Trading Card Product Portfolio
- 12.1.5 Pokémon Recent Developments
- 12.2 Fanatics
- 12.2.1 Fanatics Company Information
- 12.2.2 Fanatics Business Overview
- 12.2.3 Fanatics Revenue in Trading Card Business (2021-2026)
- 12.2.4 Fanatics Trading Card Product Portfolio
- 12.2.5 Fanatics Recent Developments
- 12.3 Wizards of the Coast
- 12.3.1 Wizards of the Coast Company Information
- 12.3.2 Wizards of the Coast Business Overview
- 12.3.3 Wizards of the Coast Revenue in Trading Card Business (2021-2026)
- 12.3.4 Wizards of the Coast Trading Card Product Portfolio
- 12.3.5 Wizards of the Coast Recent Developments
- 12.4 Kayou
- 12.4.1 Kayou Company Information
- 12.4.2 Kayou Business Overview
- 12.4.3 Kayou Revenue in Trading Card Business (2021-2026)
- 12.4.4 Kayou Trading Card Product Portfolio
- 12.4.5 Kayou Recent Developments
- 12.5 Konami
- 12.5.1 Konami Company Information
- 12.5.2 Konami Business Overview
- 12.5.3 Konami Revenue in Trading Card Business (2021-2026)
- 12.5.4 Konami Trading Card Product Portfolio
- 12.5.5 Konami Recent Developments
- 12.6 Bandai Namco
- 12.6.1 Bandai Namco Company Information
- 12.6.2 Bandai Namco Business Overview
- 12.6.3 Bandai Namco Revenue in Trading Card Business (2021-2026)
- 12.6.4 Bandai Namco Trading Card Product Portfolio
- 12.6.5 Bandai Namco Recent Developments
- 12.7 Panini
- 12.7.1 Panini Company Information
- 12.7.2 Panini Business Overview
- 12.7.3 Panini Revenue in Trading Card Business (2021-2026)
- 12.7.4 Panini Trading Card Product Portfolio
- 12.7.5 Panini Recent Developments
- 12.8 Suplay
- 12.8.1 Suplay Company Information
- 12.8.2 Suplay Business Overview
- 12.8.3 Suplay Revenue in Trading Card Business (2021-2026)
- 12.8.4 Suplay Trading Card Product Portfolio
- 12.8.5 Suplay Recent Developments
- 12.9 Ravensburger
- 12.9.1 Ravensburger Company Information
- 12.9.2 Ravensburger Business Overview
- 12.9.3 Ravensburger Revenue in Trading Card Business (2021-2026)
- 12.9.4 Ravensburger Trading Card Product Portfolio
- 12.9.5 Ravensburger Recent Developments
- 12.10 The Upper Deck
- 12.10.1 The Upper Deck Company Information
- 12.10.2 The Upper Deck Business Overview
- 12.10.3 The Upper Deck Revenue in Trading Card Business (2021-2026)
- 12.10.4 The Upper Deck Trading Card Product Portfolio
- 12.10.5 The Upper Deck Recent Developments
- 12.11 Bushiroad
- 12.11.1 Bushiroad Company Information
- 12.11.2 Bushiroad Business Overview
- 12.11.3 Bushiroad Revenue in Trading Card Business (2021-2026)
- 12.11.4 Bushiroad Trading Card Product Portfolio
- 12.11.5 Bushiroad Recent Developments
- 12.12 Jason Anime
- 12.12.1 Jason Anime Company Information
- 12.12.2 Jason Anime Business Overview
- 12.12.3 Jason Anime Revenue in Trading Card Business (2021-2026)
- 12.12.4 Jason Anime Trading Card Product Portfolio
- 12.12.5 Jason Anime Recent Developments
- 12.13 Tomy Company
- 12.13.1 Tomy Company Company Information
- 12.13.2 Tomy Company Business Overview
- 12.13.3 Tomy Company Revenue in Trading Card Business (2021-2026)
- 12.13.4 Tomy Company Trading Card Product Portfolio
- 12.13.5 Tomy Company Recent Developments
13 Report Conclusion
14 Disclaimer
GET THE RESEARCH
Choose your license.
Choose who needs access.
All options are for this report and research series.
PDF by email within 3–5 working days after payment confirmation.
Talk to an analyst