APO RESEARCH · REPORT
Industrial Rotary Encoders
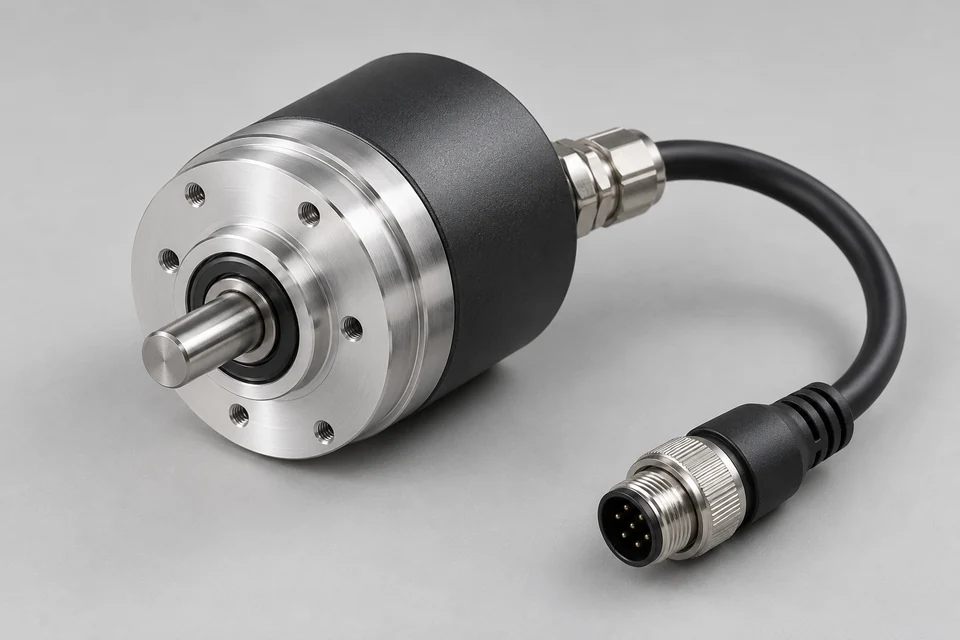
Industrial rotary encoders are precision sensors that detect and convert the angular position, rotation speed, and direction of a rotating shaft into electrical signals for monitoring and control.
Product & engineering
Understand the product.
Industrial rotary encoders are precision sensors that detect and convert the angular position, rotation speed, and direction of a rotating shaft into electrical signals for monitoring and control. These devices are fundamental components in modern industrial automation systems, enabling precise motion control, feedback mechanisms, and system synchronization. By translating mechanical rotation into digital or analog output, rotary encoders form the backbone of closed-loop systems in factory automation, robotics, CNC machinery, and more.
The concept of rotary encoding has evolved significantly since its early adoption in mechanical counters and analog systems. With the advent of digital control in the 1960s and 70s, the first incremental encoders appeared, using optical principles to detect shaft rotation. These early designs laid the groundwork for today’s high-resolution, multi-turn, and intelligent encoder systems that support advanced digital communication protocols and integrated diagnostics.
Rotary encoders are generally classified into two major types: incremental and absolute. Incremental encoders generate a continuous stream of pulses relative to shaft movement. The pulse count determines the relative position or speed but does not retain positional information upon power loss. In contrast, absolute encoders assign a unique digital value to each shaft position. This position remains constant and recoverable even after power interruptions, making absolute encoders essential in safety-critical or precision positioning applications. The distinction between incremental and absolute encoders is often compared to a stopwatch versus a clock: one measures elapsed movement from a known start, while the other continuously displays current position.
Modern industrial rotary encoders utilize various sensing technologies, including optical, magnetic, capacitive, and inductive detection methods. Optical encoders are the most common in high-precision applications, where a light source and photodetector track rotation through a code disk. Magnetic encoders offer higher resistance to contaminants and are preferred in harsh environments. Capacitive and inductive encoders provide alternative methods with lower power consumption or increased robustness.
The output of rotary encoders varies based on design and application. Incremental encoders typically output square-wave pulses on two channels (A and B), often with an optional index pulse (Z) per revolution. Absolute encoders produce digital signals representing the shaft position in either binary or gray code, transmitted in parallel or serial formats. Key serial protocols include SSI (Synchronous Serial Interface), EnDat, HIPERFACE, and BiSS. SSI is widely used in European markets and provides point-to-point unidirectional communication. EnDat, developed by HEIDENHAIN, supports bidirectional data exchange, encoder diagnostics, and electronic zeroing. HIPERFACE, a protocol by Max Stegmann GmbH, combines analog sin/cos signals with digital RS-485 communication. BiSS, an open-source digital protocol, offers fast, real-time position data exchange and register access, with high data integrity and low latency.
In addition to dedicated encoder protocols, industrial rotary encoders are often integrated into general-purpose fieldbus networks such as DeviceNet, PROFIBUS, and Interbus. DeviceNet, based on the CAN bus standard, enables devices to receive both power and signal over the same network. PROFIBUS offers two key profiles: FMS for supervisory control and DP for device-level real-time communication. Interbus, with its unique token-ring architecture, supports long-distance and high-reliability encoder networking.
Rotary encoder manufacturing involves multiple precision engineering steps. Optical encoders require micro-fabricated code disks with transparent and opaque segments, precision LED emitters, and photodetectors aligned with minimal tolerance. Magnetic encoders involve precision alignment of permanent magnets with Hall-effect or magnetoresistive sensors. The mechanical structure must ensure high radial and axial shaft load capacity, vibration tolerance, and environmental protection, often in compliance with IP ratings. Advanced encoders integrate microprocessors for signal processing, error correction, and smart diagnostics.
In the context of industrial automation, rotary encoders play a vital role in motion control, where they enable accurate position feedback for servo motors, synchronized operation of conveyor systems, and real-time monitoring of rotary elements. Their use spans a wide range of industries and applications. In material handling systems such as forklifts, pallet trucks, and light conveyors, incremental encoders are used to track wheel rotation and lift positioning. In machine tools like lathes, mills, and grinders, encoders are essential for axis control and precision feedback. Robotics applications demand high-resolution absolute encoders for multi-axis joint articulation and safety verification. In mining and metal processing, rotary encoders control conveyor belts, crushers, and rolling mills under harsh environments. Railways use encoders for train positioning, door control, and platform gate synchronization. In agriculture, encoders support automated systems in tractors, seeders, and balers. Off-highway machinery such as excavators and loaders rely on encoders for position and movement control under rugged conditions. In fluid machinery like pumps, chillers, and compressors, encoders monitor rotational speed and phase. Pulp and paper processing uses encoders for roller synchronization and tension control. Additional applications include packaging machines, textile machines, and various specialized automation systems across sectors.
The importance of rotary encoders is growing as industrial systems increasingly demand precision, safety, real-time data, and integration with digital control architectures. As the industrial sector advances toward greater automation, digitalization, and predictive maintenance, the role of intelligent and network-capable rotary encoders will become even more central to factory operations and equipment performance.
This report provides a comprehensive analysis of the global industrial rotary encoder market for the period 2020 to 2031, focusing exclusively on encoder applications within the general industrial automation sector. The analytical scope has been deliberately and precisely defined to exclude sectors such as automotive, medical devices, and semiconductor manufacturing, where encoder applications are substantial but governed by distinct technological requirements, regulatory environments, and value chains. Accordingly, all production and revenue statistics for encoder manufacturers featured in this study have been carefully adjusted to remove contributions from these excluded sectors, ensuring that the data reflects only the usage and demand patterns relevant to core industrial automation domains. For example, approximately 11% of Heidenhain’s encoder-related revenue derives from medical equipment, while around 27% of Tamagawa Seiki’s encoder shipments serve the automotive sector—these proportions have been identified and removed from the calculations to maintain data accuracy and consistency with the defined scope. The market analysis is structured around major industrial application categories, including material handling (e.g., forklifts, pallet trucks, light conveyors), machine tools (e.g., milling, turning, grinding machines), industrial robots, mining and metal processing (e.g., grinders, converters, heavy conveyors), railway systems (e.g., trains, metros, platform doors), agriculture (e.g., tractors, balers, seeders), off-highway machinery (e.g., excavators, wheel loaders), fluid machinery (e.g., pumps, compressors, chillers), pulp and paper (e.g., printing machines, dryers, rollers), packaging machinery, textile machinery, and other general industrial equipment. It is important to emphasize that this report does not represent the global rotary encoder market in its entirety, but rather a rigorously defined segment that isolates encoder demand within industrial automation, providing a focused and consistent basis for evaluating market trends, competitive dynamics, and regional developments over the forecast period.
According to APO Research, from 2020 to 2024, the global industrial rotary encoder market From 2020 to 2024, the global industrial rotary encoder market expanded from 9.13 million units to 10.70 million units, representing a compound annual growth rate (CAGR) of 4.04%. The overall CAGR was moderated by a market slowdown in 2024, during which several leading manufacturers and the broader industrial automation sector experienced weaker performance. By comparison, the CAGR for the period 2020 to 2023 was significantly higher at 6.66%.
Market revenue grew from USD 1.52 billion to USD 1.89 billion, reflecting a CAGR of 5.52 percent, driven by increased demand for precision automation in emerging industries and resilient investments in infrastructure and industrial equipment despite global macroeconomic uncertainty. The average selling price increased from USD 166.7 in 2020 to USD 176.3 in 2024. This rise is attributed to the proliferation of smart factories, the growing preference for higher-spec encoders with better IP ratings, higher resolution, and digital connectivity such as integration with fieldbus and Ethernet protocols, and temporary component shortages during the COVID and post-COVID era. In terms of regional distribution in 2024, Europe remains the largest manufacturing base with an output of 3.99 million units, supported by strong demand in machine tools, robotics, and railway automation in Germany, Italy, and France. Asia-Pacific follows closely, driven by China's booming industrial robotics sector, Japan's leadership in precision machinery, and India's rising investment in agricultural and packaging automation. North America, mainly the United States, contributed 1.55 million units, with particular strength in fluid machinery, packaging, and off-highway equipment. The rest of the world, including South America, Eastern Europe, and the Middle East, representing a growing market particularly in mining and metal processing.
The application breakdown by market size share in 2024 is as follows: material handling accounts for 13.8 percent, machine tools 18.7 percent, industrial robots’ 13.4 percent, mining and metal processing 12.7 percent, railway 5.6 percent, agriculture 4 percent, off-highway machinery 12.1 percent, fluid machinery 8.1 percent, pulp and paper 5.9 percent, packaging machinery 3 percent, textile machinery 1.9 percent, and other 1 percent. The forecast for 2025 to 2031 projects continued growth. By 2031, the market is expected to reach 16.02 million units and USD 3.08 billion in revenue, with a CAGR of 6.55 percent in volume and 7.02 percent in value. Average unit prices are projected to slightly increase to USD 169.8, reflecting improved manufacturing efficiency, growing competition, and product standardization in mid-range applications.
The industrial rotary encoder market remains moderately consolidated. Leading global companies include Heidenhain of Germany, strong in machine tools, robots, and harsh environments; Dynapar of the USA, broadest range of encoders for industrial applications; SICK AG of Germany, offering a diversified portfolio across logistics, robotics, and process automation; Tamagawa Seiki of Japan, a core supplier to Japanese machine tool and railway manufacturers; as well as Nemicon, Baumer, Pepperl+Fuchs, Omron, and Kubler, which are key players in regional markets and industry-specific niches. Emerging Asian suppliers, especially from China, are expanding their presence in mid- and low-end segments by offering cost-effective encoders with increasingly acceptable performance levels. This trend is reshaping the competitive landscape, especially in material handling, fluid machinery, and packaging sectors.
A sensor converts a specified physical quantity into a usable signal; a complete measurement also depends on excitation, signal conditioning, installation and calibration. The transducer, instrument and measurement service are different supplied objects.
What turns activity into demand
The number of equipped measurement points and replacement intervals links installed systems to sensor purchases. Instruments, individual sensing elements and calibration services must be counted at their respective supplied boundaries.
The commercial boundary
For Industrial Rotary Encoders, distinguish the supplied product from its inputs and the complete application. Report types and applications may overlap; retain the selected edition's product definition, geography, period, unit and transaction basis when comparing estimates.
Which conditions determine usable industrial rotary encoders performance?
Industrial rotary encoders are precision sensors that detect and convert the angular position, rotation speed, and direction of a rotating shaft into electrical signals for monitoring and control. Assess accuracy, bandwidth and drift under the actual temperature and interference conditions, with the stated calibration and mounting method. Sampling rate alone does not define useful measurement bandwidth or decision latency.
Selected research
Industry Research
Industrial Rotary Encoders Industry Research Report 2026
Market perspective
Industrial rotary encoders are precision sensors that detect and convert the angular position, rotation speed, and direction of a rotating shaft into electrical signals for monitoring and control. These devices are fundamental components in modern industrial automation systems, enabling precise motion control, feedback mechanisms, and system synchronization. By translating mechanical rotation into digital or analog output, rotary encoders form the backbone of closed-loop systems in factory automation, robotics, CNC machinery, and more.
The concept of rotary encoding has evolved significantly since its early adoption in mechanical counters and analog systems. With the advent of digital control in the 1960s and 70s, the first incremental encoders appeared, using optical principles to detect shaft rotation. These early designs laid the groundwork for today’s high-resolution, multi-turn, and intelligent encoder systems that support advanced digital communication protocols and integrated diagnostics.
Rotary encoders are generally classified into two major types: incremental and absolute. Incremental encoders generate a continuous stream of pulses relative to shaft movement. The pulse count determines the relative position or speed but does not retain positional information upon power loss. In contrast, absolute encoders assign a unique digital value to each shaft position. This position remains constant and recoverable even after power interruptions, making absolute encoders essential in safety-critical or precision positioning applications. The distinction between incremental and absolute encoders is often compared to a stopwatch versus a clock: one measures elapsed movement from a known start, while the other continuously displays current position.
Read the full market overview
Modern industrial rotary encoders utilize various sensing technologies, including optical, magnetic, capacitive, and inductive detection methods. Optical encoders are the most common in high-precision applications, where a light source and photodetector track rotation through a code disk. Magnetic encoders offer higher resistance to contaminants and are preferred in harsh environments. Capacitive and inductive encoders provide alternative methods with lower power consumption or increased robustness.
The output of rotary encoders varies based on design and application. Incremental encoders typically output square-wave pulses on two channels (A and B), often with an optional index pulse (Z) per revolution. Absolute encoders produce digital signals representing the shaft position in either binary or gray code, transmitted in parallel or serial formats. Key serial protocols include SSI (Synchronous Serial Interface), EnDat, HIPERFACE, and BiSS. SSI is widely used in European markets and provides point-to-point unidirectional communication. EnDat, developed by HEIDENHAIN, supports bidirectional data exchange, encoder diagnostics, and electronic zeroing. HIPERFACE, a protocol by Max Stegmann GmbH, combines analog sin/cos signals with digital RS-485 communication. BiSS, an open-source digital protocol, offers fast, real-time position data exchange and register access, with high data integrity and low latency.
In addition to dedicated encoder protocols, industrial rotary encoders are often integrated into general-purpose fieldbus networks such as DeviceNet, PROFIBUS, and Interbus. DeviceNet, based on the CAN bus standard, enables devices to receive both power and signal over the same network. PROFIBUS offers two key profiles: FMS for supervisory control and DP for device-level real-time communication. Interbus, with its unique token-ring architecture, supports long-distance and high-reliability encoder networking.
Rotary encoder manufacturing involves multiple precision engineering steps. Optical encoders require micro-fabricated code disks with transparent and opaque segments, precision LED emitters, and photodetectors aligned with minimal tolerance. Magnetic encoders involve precision alignment of permanent magnets with Hall-effect or magnetoresistive sensors. The mechanical structure must ensure high radial and axial shaft load capacity, vibration tolerance, and environmental protection, often in compliance with IP ratings. Advanced encoders integrate microprocessors for signal processing, error correction, and smart diagnostics.
In the context of industrial automation, rotary encoders play a vital role in motion control, where they enable accurate position feedback for servo motors, synchronized operation of conveyor systems, and real-time monitoring of rotary elements. Their use spans a wide range of industries and applications. In material handling systems such as forklifts, pallet trucks, and light conveyors, incremental encoders are used to track wheel rotation and lift positioning. In machine tools like lathes, mills, and grinders, encoders are essential for axis control and precision feedback. Robotics applications demand high-resolution absolute encoders for multi-axis joint articulation and safety verification. In mining and metal processing, rotary encoders control conveyor belts, crushers, and rolling mills under harsh environments. Railways use encoders for train positioning, door control, and platform gate synchronization. In agriculture, encoders support automated systems in tractors, seeders, and balers. Off-highway machinery such as excavators and loaders rely on encoders for position and movement control under rugged conditions. In fluid machinery like pumps, chillers, and compressors, encoders monitor rotational speed and phase. Pulp and paper processing uses encoders for roller synchronization and tension control. Additional applications include packaging machines, textile machines, and various specialized automation systems across sectors.
The importance of rotary encoders is growing as industrial systems increasingly demand precision, safety, real-time data, and integration with digital control architectures. As the industrial sector advances toward greater automation, digitalization, and predictive maintenance, the role of intelligent and network-capable rotary encoders will become even more central to factory operations and equipment performance.
This report provides a comprehensive analysis of the global industrial rotary encoder market for the period 2020 to 2031, focusing exclusively on encoder applications within the general industrial automation sector. The analytical scope has been deliberately and precisely defined to exclude sectors such as automotive, medical devices, and semiconductor manufacturing, where encoder applications are substantial but governed by distinct technological requirements, regulatory environments, and value chains. Accordingly, all production and revenue statistics for encoder manufacturers featured in this study have been carefully adjusted to remove contributions from these excluded sectors, ensuring that the data reflects only the usage and demand patterns relevant to core industrial automation domains. For example, approximately 11% of Heidenhain’s encoder-related revenue derives from medical equipment, while around 27% of Tamagawa Seiki’s encoder shipments serve the automotive sector—these proportions have been identified and removed from the calculations to maintain data accuracy and consistency with the defined scope. The market analysis is structured around major industrial application categories, including material handling (e.g., forklifts, pallet trucks, light conveyors), machine tools (e.g., milling, turning, grinding machines), industrial robots, mining and metal processing (e.g., grinders, converters, heavy conveyors), railway systems (e.g., trains, metros, platform doors), agriculture (e.g., tractors, balers, seeders), off-highway machinery (e.g., excavators, wheel loaders), fluid machinery (e.g., pumps, compressors, chillers), pulp and paper (e.g., printing machines, dryers, rollers), packaging machinery, textile machinery, and other general industrial equipment. It is important to emphasize that this report does not represent the global rotary encoder market in its entirety, but rather a rigorously defined segment that isolates encoder demand within industrial automation, providing a focused and consistent basis for evaluating market trends, competitive dynamics, and regional developments over the forecast period.
According to APO Research, from 2020 to 2024, the global industrial rotary encoder market From 2020 to 2024, the global industrial rotary encoder market expanded from 9.13 million units to 10.70 million units, representing a compound annual growth rate (CAGR) of 4.04%. The overall CAGR was moderated by a market slowdown in 2024, during which several leading manufacturers and the broader industrial automation sector experienced weaker performance. By comparison, the CAGR for the period 2020 to 2023 was significantly higher at 6.66%.
Market revenue grew from USD 1.52 billion to USD 1.89 billion, reflecting a CAGR of 5.52 percent, driven by increased demand for precision automation in emerging industries and resilient investments in infrastructure and industrial equipment despite global macroeconomic uncertainty. The average selling price increased from USD 166.7 in 2020 to USD 176.3 in 2024. This rise is attributed to the proliferation of smart factories, the growing preference for higher-spec encoders with better IP ratings, higher resolution, and digital connectivity such as integration with fieldbus and Ethernet protocols, and temporary component shortages during the COVID and post-COVID era. In terms of regional distribution in 2024, Europe remains the largest manufacturing base with an output of 3.99 million units, supported by strong demand in machine tools, robotics, and railway automation in Germany, Italy, and France. Asia-Pacific follows closely, driven by China's booming industrial robotics sector, Japan's leadership in precision machinery, and India's rising investment in agricultural and packaging automation. North America, mainly the United States, contributed 1.55 million units, with particular strength in fluid machinery, packaging, and off-highway equipment. The rest of the world, including South America, Eastern Europe, and the Middle East, representing a growing market particularly in mining and metal processing.
The application breakdown by market size share in 2024 is as follows: material handling accounts for 13.8 percent, machine tools 18.7 percent, industrial robots’ 13.4 percent, mining and metal processing 12.7 percent, railway 5.6 percent, agriculture 4 percent, off-highway machinery 12.1 percent, fluid machinery 8.1 percent, pulp and paper 5.9 percent, packaging machinery 3 percent, textile machinery 1.9 percent, and other 1 percent. The forecast for 2025 to 2031 projects continued growth. By 2031, the market is expected to reach 16.02 million units and USD 3.08 billion in revenue, with a CAGR of 6.55 percent in volume and 7.02 percent in value. Average unit prices are projected to slightly increase to USD 169.8, reflecting improved manufacturing efficiency, growing competition, and product standardization in mid-range applications.
The industrial rotary encoder market remains moderately consolidated. Leading global companies include Heidenhain of Germany, strong in machine tools, robots, and harsh environments; Dynapar of the USA, broadest range of encoders for industrial applications; SICK AG of Germany, offering a diversified portfolio across logistics, robotics, and process automation; Tamagawa Seiki of Japan, a core supplier to Japanese machine tool and railway manufacturers; as well as Nemicon, Baumer, Pepperl+Fuchs, Omron, and Kubler, which are key players in regional markets and industry-specific niches. Emerging Asian suppliers, especially from China, are expanding their presence in mid- and low-end segments by offering cost-effective encoders with increasingly acceptable performance levels. This trend is reshaping the competitive landscape, especially in material handling, fluid machinery, and packaging sectors.
The global Industrial Rotary Encoders market was valued at US$ million in 2025 and is projected to reach US$ million by 2032, implying a CAGR of % over 2026–2032.
The North America market for Industrial Rotary Encoders is forecast to increase from US$ million in 2026 to US$ million by 2032, corresponding to a CAGR of % over 2026–2032.
The Europe market for Industrial Rotary Encoders is projected to rise from US$ million in 2026 to US$ million by 2032, registering a CAGR of % over 2026–2032.
The Asia Pacific market for Industrial Rotary Encoders is expected to grow from US$ million in 2026 to US$ million by 2032, at a CAGR of % over 2026–2032.
Leading global manufacturers of Industrial Rotary Encoders include , among others. In 2025, the top three vendors together accounted for approximately % of global revenue.
Report Scope
This report quantifies the global Industrial Rotary Encoders market in revenue (US$ million) and, where applicable, sales volume (k units), using 2025 as the base year and providing annual historical and forecast data for 2021–2032.
It standardizes definitions of types and applications, harmonizes vendor attribution, and presents comparable time series by company, type, application, and region/country, including indicative price bands (US$/k units) and concentration ratios (CR5/CR10).
The outputs are intended to support strategy development, budgeting, and performance benchmarking for manufacturers, new entrants, channel partners, and investors; the report also reviews technology shifts and notable product introductions relevant to Industrial Rotary Encoders.
Key Companies & Market Share Insights
This section profiles leading manufacturers, combining 2021–2025 results with a 2026–2032 outlook. It reports revenue, market share, price bands, product and application mix, regional and channel mix, and key developments (M&A, capacity additions, certifications). It also provides global revenue, average price, and—where applicable—sales volume by manufacturer, and calculates CR5/CR10 and rank changes to support comparative benchmarking.
Industrial Rotary Encoders Market by Company
Heidenhain
Dynapar
Sick AG
Nemicon
Baumer
Tamagawa Seiki
Pepperl+Fuchs
Omron
Fritz Kübler GmbH
Changchun Yuheng Optics
Industrial Rotary Encoders Segment by Type
Incremental Encoder
Absolute Encoder
Industrial Rotary Encoders Segment by Application
Material Handling
Machine Tools
Mining & Metal Processing
Industrial Robots
Railway
Agriculture
Off-Highway Machinery
Fluid Machinery
Pulp & Paper
Packaging Machinery
Industrial Rotary Encoders Segment by Region
North America
United States
Canada
Mexico
Europe
Germany
France
U.K.
Italy
Russia
Spain
Netherlands
Switzerland
Sweden
Poland
Asia-Pacific
China
Japan
South Korea
India
Australia
Taiwan
Southeast Asia
South America
Brazil
Argentina
Chile
Middle East & Africa
Egypt
South Africa
Israel
Türkiye
GCC Countries
Key Drivers & Barriers
High-impact rendering factors and drivers have been studied in this report to aid the readers to understand the general development. Moreover, the report includes restraints and challenges that may act as stumbling blocks on the way of the players. This will assist the users to be attentive and make informed decisions related to business. Specialists have also laid their focus on the upcoming business prospects.
Reasons to Buy This Report
1. This report will help the readers to understand the competition within the industries and strategies for the competitive environment to enhance the potential profit. The report also focuses on the competitive landscape of the global Industrial Rotary Encoders market, and introduces in detail the market share, industry ranking, competitor ecosystem, market performance, new product development, operation situation, expansion, and acquisition. etc. of the main players, which helps the readers to identify the main competitors and deeply understand the competition pattern of the market.
2. This report will help stakeholders to understand the global industry status and trends of Industrial Rotary Encoders and provides them with information on key market drivers, restraints, challenges, and opportunities.
3. This report will help stakeholders to understand competitors better and gain more insights to strengthen their position in their businesses. The competitive landscape section includes the market share and rank (in volume and value), competitor ecosystem, new product development, expansion, and acquisition.
4. This report stays updated with novel technology integration, features, and the latest developments in the market
5. This report helps stakeholders to gain insights into which regions to target globally
6. This report helps stakeholders to gain insights into the end-user perception concerning the adoption of Industrial Rotary Encoders.
7. This report helps stakeholders to identify some of the key players in the market and understand their valuable contribution.
Chapter Outline
Chapter 1: Research objectives, research methods, data sources, data cross-validation;
Chapter 2: Introduces the report scope of the report, executive summary of different market segments (by region, product type, application, etc), including the market size of each market segment, future development potential, and so on. It offers a high-level view of the current state of the market and its likely evolution in the short to mid-term, and long term.
Chapter 3: Detailed analysis of Industrial Rotary Encoders manufacturers competitive landscape, price, production and value market share, latest development plan, merger, and acquisition information, etc.
Chapter 4: Provides profiles of key players, introducing the basic situation of the main companies in the market in detail, including product production/output, value, price, gross margin, product introduction, recent development, etc.
Chapter 5: Production/output, value of Industrial Rotary Encoders by region/country. It provides a quantitative analysis of the market size and development potential of each region in the next six years.
Chapter 6: Consumption of Industrial Rotary Encoders in regional level and country level. It provides a quantitative analysis of the market size and development potential of each region and its main countries and introduces the market development, future development prospects, market space, and production of each country in the world.
Chapter 7: Provides the analysis of various market segments by type, covering the market size and development potential of each market segment, to help readers find the blue ocean market in different market segments.
Chapter 8: Provides the analysis of various market segments by application, covering the market size and development potential of each market segment, to help readers find the blue ocean market in different downstream markets.
Chapter 9: Analysis of industrial chain, including the upstream and downstream of the industry.
Chapter 10: Introduces the market dynamics, latest developments of the market, the driving factors and restrictive factors of the market, the challenges and risks faced by manufacturers in the industry, and the analysis of relevant policies in the industry.
Chapter 11: The main points and conclusions of the report.
More report detail
Tables and figures
Scope & coverage.
Types
- Incremental Encoder
- Absolute Encoder
Applications
- Material Handling
- Machine Tools
- Mining & Metal Processing
- Industrial Robots
- Railway
- Agriculture
- Off-Highway Machinery
- Fluid Machinery
- Pulp & Paper
- Packaging Machinery
Companies covered
- Heidenhain
- Dynapar
- Sick AG
- Nemicon
- Baumer
- Tamagawa Seiki
- Pepperl+Fuchs
- Omron
- Fritz Kübler GmbH
- Changchun Yuheng Optics
Inside the report.
1 Preface
- 1.1 Scope of Report
- 1.2 Reasons for Doing This Study
- 1.3 Research Methodology
- 1.4 Research Process
- 1.5 Data Source
- 1.5.1 Secondary Sources
- 1.5.2 Primary Sources
2 Market Overview
- 2.1 Product Definition
- 2.2 Industrial Rotary Encoders by Type
- 2.2.1 Market Value Comparison by Type (2021 VS 2025 VS 2032) & (US$ Million)
- 2.2.2 Incremental Encoder
- 2.2.3 Absolute Encoder
- 2.3 Industrial Rotary Encoders by Application
- 2.3.1 Market Value Comparison by Application (2021 VS 2025 VS 2032) & (US$ Million)
- 2.3.2 Material Handling
- 2.3.3 Machine Tools
- 2.3.4 Mining & Metal Processing
- 2.3.5 Industrial Robots
- 2.3.6 Railway
- 2.3.7 Agriculture
- 2.3.8 Off-Highway Machinery
- 2.3.9 Fluid Machinery
- 2.3.10 Pulp & Paper
- 2.3.11 Packaging Machinery
- 2.4 Global Market Growth Prospects
- 2.4.1 Global Industrial Rotary Encoders Production Value Estimates and Forecasts (2021-2032)
- 2.4.2 Global Industrial Rotary Encoders Production Capacity Estimates and Forecasts (2021-2032)
- 2.4.3 Global Industrial Rotary Encoders Production Estimates and Forecasts (2021-2032)
- 2.4.4 Global Industrial Rotary Encoders Market Average Price (2021-2032)
3 Market Competitive Landscape by Manufacturers
- 3.1 Global Industrial Rotary Encoders Production by Manufacturers (2021-2026)
- 3.2 Global Industrial Rotary Encoders Production Value by Manufacturers (2021-2026)
- 3.3 Global Industrial Rotary Encoders Average Price by Manufacturers (2021-2026)
- 3.4 Global Industrial Rotary Encoders Industry Manufacturers Ranking, 2024 VS 2025 VS 2026
- 3.5 Global Industrial Rotary Encoders Key Manufacturers, Manufacturing Sites & Headquarters
- 3.6 Global Industrial Rotary Encoders Manufacturers, Product Type & Application
- 3.7 Global Industrial Rotary Encoders Manufacturers Established Date
- 3.8 Global Industrial Rotary Encoders Market CR5 and HHI
- 3.9 Global Manufacturers Mergers & Acquisition
4 Manufacturers Profiled
- 4.1 Heidenhain
- 4.1.1 Heidenhain Industrial Rotary Encoders Company Information
- 4.1.2 Heidenhain Industrial Rotary Encoders Business Overview
- 4.1.3 Heidenhain Industrial Rotary Encoders Production, Value and Gross Margin (2021-2026)
- 4.1.4 Heidenhain Product Portfolio
- 4.1.5 Heidenhain Recent Developments
- 4.2 Dynapar
- 4.2.1 Dynapar Industrial Rotary Encoders Company Information
- 4.2.2 Dynapar Industrial Rotary Encoders Business Overview
- 4.2.3 Dynapar Industrial Rotary Encoders Production, Value and Gross Margin (2021-2026)
- 4.2.4 Dynapar Product Portfolio
- 4.2.5 Dynapar Recent Developments
- 4.3 Sick AG
- 4.3.1 Sick AG Industrial Rotary Encoders Company Information
- 4.3.2 Sick AG Industrial Rotary Encoders Business Overview
- 4.3.3 Sick AG Industrial Rotary Encoders Production, Value and Gross Margin (2021-2026)
- 4.3.4 Sick AG Product Portfolio
- 4.3.5 Sick AG Recent Developments
- 4.4 Nemicon
- 4.4.1 Nemicon Industrial Rotary Encoders Company Information
- 4.4.2 Nemicon Industrial Rotary Encoders Business Overview
- 4.4.3 Nemicon Industrial Rotary Encoders Production, Value and Gross Margin (2021-2026)
- 4.4.4 Nemicon Product Portfolio
- 4.4.5 Nemicon Recent Developments
- 4.5 Baumer
- 4.5.1 Baumer Industrial Rotary Encoders Company Information
- 4.5.2 Baumer Industrial Rotary Encoders Business Overview
- 4.5.3 Baumer Industrial Rotary Encoders Production, Value and Gross Margin (2021-2026)
- 4.5.4 Baumer Product Portfolio
- 4.5.5 Baumer Recent Developments
- 4.6 Tamagawa Seiki
- 4.6.1 Tamagawa Seiki Industrial Rotary Encoders Company Information
- 4.6.2 Tamagawa Seiki Industrial Rotary Encoders Business Overview
- 4.6.3 Tamagawa Seiki Industrial Rotary Encoders Production, Value and Gross Margin (2021-2026)
- 4.6.4 Tamagawa Seiki Product Portfolio
- 4.6.5 Tamagawa Seiki Recent Developments
- 4.7 Pepperl+Fuchs
- 4.7.1 Pepperl+Fuchs Industrial Rotary Encoders Company Information
- 4.7.2 Pepperl+Fuchs Industrial Rotary Encoders Business Overview
- 4.7.3 Pepperl+Fuchs Industrial Rotary Encoders Production, Value and Gross Margin (2021-2026)
- 4.7.4 Pepperl+Fuchs Product Portfolio
- 4.7.5 Pepperl+Fuchs Recent Developments
- 4.8 Omron
- 4.8.1 Omron Industrial Rotary Encoders Company Information
- 4.8.2 Omron Industrial Rotary Encoders Business Overview
- 4.8.3 Omron Industrial Rotary Encoders Production, Value and Gross Margin (2021-2026)
- 4.8.4 Omron Product Portfolio
- 4.8.5 Omron Recent Developments
- 4.9 Fritz Kübler GmbH
- 4.9.1 Fritz Kübler GmbH Industrial Rotary Encoders Company Information
- 4.9.2 Fritz Kübler GmbH Industrial Rotary Encoders Business Overview
- 4.9.3 Fritz Kübler GmbH Industrial Rotary Encoders Production, Value and Gross Margin (2021-2026)
- 4.9.4 Fritz Kübler GmbH Product Portfolio
- 4.9.5 Fritz Kübler GmbH Recent Developments
- 4.10 Changchun Yuheng Optics
- 4.10.1 Changchun Yuheng Optics Industrial Rotary Encoders Company Information
- 4.10.2 Changchun Yuheng Optics Industrial Rotary Encoders Business Overview
- 4.10.3 Changchun Yuheng Optics Industrial Rotary Encoders Production, Value and Gross Margin (2021-2026)
- 4.10.4 Changchun Yuheng Optics Product Portfolio
- 4.10.5 Changchun Yuheng Optics Recent Developments
5 Global Industrial Rotary Encoders Production by Region
- 5.1 Global Industrial Rotary Encoders Production Estimates and Forecasts by Region: 2021 VS 2025 VS 2032
- 5.2 Global Industrial Rotary Encoders Production by Region: 2021-2032
- 5.2.1 Global Industrial Rotary Encoders Production by Region: 2021-2026
- 5.2.2 Global Industrial Rotary Encoders Production Forecast by Region (2027-2032)
- 5.3 Global Industrial Rotary Encoders Production Value Estimates and Forecasts by Region: 2021 VS 2025 VS 2032
- 5.4 Global Industrial Rotary Encoders Production Value by Region: 2021-2032
- 5.4.1 Global Industrial Rotary Encoders Production Value by Region: 2021-2026
- 5.4.2 Global Industrial Rotary Encoders Production Value Forecast by Region (2027-2032)
- 5.5 Global Industrial Rotary Encoders Market Price Analysis by Region (2021-2026)
- 5.6 Global Industrial Rotary Encoders Production and Value, YOY Growth
- 5.6.1 North America Industrial Rotary Encoders Production Value Estimates and Forecasts (2021-2032)
- 5.6.2 Europe Industrial Rotary Encoders Production Value Estimates and Forecasts (2021-2032)
- 5.6.3 China Industrial Rotary Encoders Production Value Estimates and Forecasts (2021-2032)
- 5.6.4 Japan Industrial Rotary Encoders Production Value Estimates and Forecasts (2021-2032)
6 Global Industrial Rotary Encoders Consumption by Region
- 6.1 Global Industrial Rotary Encoders Consumption Estimates and Forecasts by Region: 2021 VS 2025 VS 2032
- 6.2 Global Industrial Rotary Encoders Consumption by Region (2021-2032)
- 6.2.1 Global Industrial Rotary Encoders Consumption by Region: 2021-2026
- 6.2.2 Global Industrial Rotary Encoders Forecasted Consumption by Region (2027-2032)
- 6.3 North America
- 6.3.1 North America Industrial Rotary Encoders Consumption Growth Rate by Country: 2021 VS 2025 VS 2032
- 6.3.2 North America Industrial Rotary Encoders Consumption by Country (2021-2032)
- 6.3.3 United States
- 6.3.4 Canada
- 6.3.5 Mexico
- 6.4 Europe
- 6.4.1 Europe Industrial Rotary Encoders Consumption Growth Rate by Country: 2021 VS 2025 VS 2032
- 6.4.2 Europe Industrial Rotary Encoders Consumption by Country (2021-2032)
- 6.4.3 Germany
- 6.4.4 France
- 6.4.5 U.K.
- 6.4.6 Italy
- 6.4.7 Russia
- 6.4.8 Spain
- 6.4.9 Netherlands
- 6.4.10 Switzerland
- 6.4.11 Sweden
- 6.4.12 Poland
- 6.5 Asia Pacific
- 6.5.1 Asia Pacific Industrial Rotary Encoders Consumption Growth Rate by Country: 2021 VS 2025 VS 2032
- 6.5.2 Asia Pacific Industrial Rotary Encoders Consumption by Country (2021-2032)
- 6.5.3 China
- 6.5.4 Japan
- 6.5.5 South Korea
- 6.5.6 India
- 6.5.7 Australia
- 6.5.8 Taiwan
- 6.5.9 Southeast Asia
- 6.6 South America, Middle East & Africa
- 6.6.1 South America, Middle East & Africa Industrial Rotary Encoders Consumption Growth Rate by Country: 2021 VS 2025 VS 2032
- 6.6.2 South America, Middle East & Africa Industrial Rotary Encoders Consumption by Country (2021-2032)
- 6.6.3 Brazil
- 6.6.4 Argentina
- 6.6.5 Chile
- 6.6.6 Turkey
- 6.6.7 GCC Countries
7 Segment by Type
- 7.1 Global Industrial Rotary Encoders Production by Type (2021-2032)
- 7.1.1 Global Industrial Rotary Encoders Production by Type (2021-2032) & (k units)
- 7.1.2 Global Industrial Rotary Encoders Production Market Share by Type (2021-2032)
- 7.2 Global Industrial Rotary Encoders Production Value by Type (2021-2032)
- 7.2.1 Global Industrial Rotary Encoders Production Value by Type (2021-2032) & (US$ Million)
- 7.2.2 Global Industrial Rotary Encoders Production Value Market Share by Type (2021-2032)
- 7.3 Global Industrial Rotary Encoders Price by Type (2021-2032)
8 Segment by Application
- 8.1 Global Industrial Rotary Encoders Production by Application (2021-2032)
- 8.1.1 Global Industrial Rotary Encoders Production by Application (2021-2032) & (k units)
- 8.1.2 Global Industrial Rotary Encoders Production Market Share by Application (2021-2032)
- 8.2 Global Industrial Rotary Encoders Production Value by Application (2021-2032)
- 8.2.1 Global Industrial Rotary Encoders Production Value by Application (2021-2032) & (US$ Million)
- 8.2.2 Global Industrial Rotary Encoders Production Value Market Share by Application (2021-2032)
- 8.3 Global Industrial Rotary Encoders Price by Application (2021-2032)
9 Value Chain and Sales Channels Analysis of the Market
- 9.1 Industrial Rotary Encoders Value Chain Analysis
- 9.1.1 Industrial Rotary Encoders Key Raw Materials
- 9.1.2 Raw Materials Key Suppliers
- 9.1.3 Industrial Rotary Encoders Production Mode & Process
- 9.2 Industrial Rotary Encoders Sales Channels Analysis
- 9.2.1 Direct Comparison with Distribution Share
- 9.2.2 Industrial Rotary Encoders Distributors
- 9.2.3 Industrial Rotary Encoders Customers
10 Global Industrial Rotary Encoders Analyzing Market Dynamics
- 10.1 Industrial Rotary Encoders Industry Trends
- 10.2 Industrial Rotary Encoders Industry Drivers
- 10.3 Industrial Rotary Encoders Industry Opportunities and Challenges
- 10.4 Industrial Rotary Encoders Industry Restraints
11 Report Conclusion
12 Disclaimer
GET THE RESEARCH
Choose your license.
Choose who needs access.
All options are for this report and research series.
PDF by email within 3–5 working days after payment confirmation.
Talk to an analyst